In a constantly evolving business landscape characterised by market fluctuations, carve-out transactions stand out as a compelling alternative for entities looking to streamline their operations and focus on and allocate resources to core business activities.
5.3.2024
The trend of global carve-out transactions remains active
Benjamin Bade & Maiju Mäkinen
Related services
We have witnessed a significant increase in complex multi-jurisdictional carve-outs in recent years, and the trend of strategic reviews and divestment of non-core assets seems to continue also in the current market.
Carve-out transactions involve the separation of a business unit or division from its parent entity, often resulting in the creation of a standalone entity distinct from its parent entity or the integration of the divested business directly into another organisation. As complex legal undertakings, carve-out transactions require careful planning, structured project management and a deep understanding of the underlying legal questions.
We have compiled below some of the key legal considerations that should be taken into account when planning and implementing a carve-out transaction in multiple jurisdictions.
Identifying the business to be separated
Separating a business unit or division requires identifying which assets, employees, commercial agreements, intellectual property rights, and premises belong to the business to be separated and are to be transferred with it. Each category of assets and agreements requires thorough legal analysis as regards transferability.
It is common that the business to be separated and the parent entity have shared assets that both entities are using. This often leads to detailed considerations regarding separation issues, such as the renegotiation of shared agreements, employee and union negotiations, and the negotiation of licensing arrangements with respect to shared intellectual property rights.
Structuring the separation
Structuring is an important first step of the planning phase whereby different structural alternatives for the transaction are analysed and ultimately decided on. These include cost and timeline aspects, regulatory requirements, and the overall complexity of implementing the final structure, among other things.
Need for transitional services and negotiating a transitional services agreement
The business to be separated is typically dependent on certain services provided by the parent entity and may require transitional services for a specific period after the completion of the carve-out. Identifying the services that can be offered after the consummation of the transaction is critical, and the detailed terms for offering such services are captured in a transitional services agreement. It is key to carefully consider the underlying service and supply agreements when scoping out the terms and conditions for the transitional services.
Regulatory framework and potential approvals from third parties
The need for any approvals under foreign direct investment regimes and the filing of merger control notifications should be assessed early on in the process, as these aspects may have a significant impact on the overall timeline.
Depending on the line of business of the company, industry-specific approvals from or notifications to local authorities in different jurisdictions may also be required to validly consummate the transaction. The transfer of employees may also trigger the obligation to carry out cooperation negotiations or to inform or consult with employee representatives or unions.
If the business to be separated requires permits or licenses for its operations, the possibility to assign these in connection with the carve-out should be assessed. The same applies to any required actions for such permits or licenses to remain in force after the completion of the transaction.
Carve-out transactions typically include the assignment of agreements from one entity to another which, as a main rule, requires the counterparty’s consent. In large transactions, the identification of the most material counterparties and the careful planning of the process to obtain consent play a key role in mitigating the risk that key agreements would be terminated by the counterparty.
Drafting and negotiating transaction documents
Understanding the interrelation between different transaction documents and how they are linked together as well as ensuring alignment across these documents is crucial for a successful carve-out transaction. In addition to the main transaction agreement, local share or asset transfer agreements and transitional services agreements are typically required. Licensing agreements, service agreements, new employment agreements or other ancillary agreements may also need to be prepared.
C&S track record in cross-border carve-out transactions
We have extensive experience in advising clients throughout the entire lifecycle of a carve-out project, and we have been involved in some of the largest and most prominent carve-out transactions in the Finnish market. Our team’s solution-oriented approach provides tailored legal solutions to guide clients through all the legal aspects of cross-border carve-out transactions, ensuring seamless execution and achieving the best possible outcome to the client. We frequently provide advice on both sell and buy-side carve-out transactions. Our team of legal experts has valuable insights in cooperating with legal advisors from multiple jurisdictions to combine legal knowledge into the best possible practical solutions for our clients.
Latest insights
Article published 28.4.2026 – Private M&A
Unlocking value in carve-outs – Why integration planning deserves top priority in every carve-out
 Article published 17.10.2025 – Intellectual Property
Is your IP safe? Eight real-life tips to avoid costly mistakes
 Article published 9.7.2025 – FDI Regulatory Service
Defence sector investments and acquisitions – key facts about the Finnish FDI regulation
 Article published 25.3.2025 – Private M&A
How to successfully run a large-scale cross-border M&A project?
Benjamin Bade, Maiju Mäkinen & Samuli Salminen
Lauri Laatunen & Janne Koivisto
Kiti Karvinen & Markus Rahnu
Carola Lindholm & Samuli Tarkiainen
Latest references
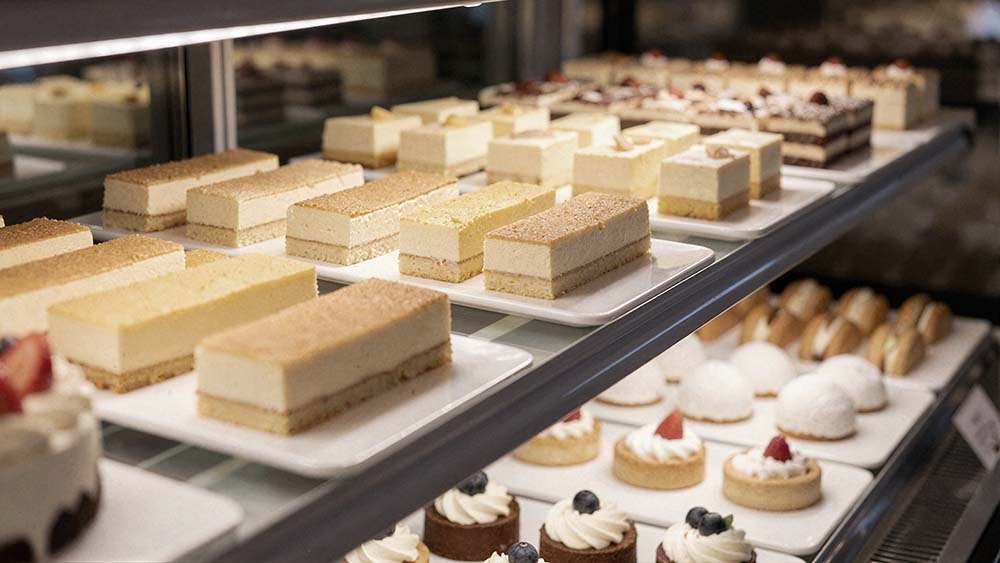
Topfoods – Acquisition of Delice Plus
We advised Topfoods Oy, a Triton-backed Geia Group company, on its acquisition of Oy Delice Plus Ab, a Finnish supplier of cakes and pastries. Through the acquisition, Topfoods strengthens its retail business and further reinforces its position in the cakes and pastries segment. Founded in 2008, Topfoods supplies selected food products to professional kitchens, the retail sector, and the food industry.
Case published 4.9.2026
HANZA – Divestment of its Nivala and Sievi operations
We advised HANZA on the divestment of its Nivala and Sievi operations. The transaction was part of HANZA’s larger strategic reorganisation, where the company optimised its Finnish manufacturing cluster. Founded in 2008, HANZA is a Swedish mechanical engineering and electronics contract manufacturing company listed on the Nasdaq Stockholm main list. HANZA has approximately 5,000 employees and annual sales of SEK 10 billion.
Case published 3.9.2026
Korona Invest – Sale of Innoflame
We advise Korona Invest and the other shareholders of Innoflame Oy on the sale of Innoflame to Sponsor Capital. The transaction makes Sponsor Capital the new majority owner of Innoflame. Korona Invest has been a shareholder of Innoflame since 2021 and, together with the other selling shareholders, has over the past five years supported the company’s growth, development and several strategically significant corporate transactions, through which Innoflame has strengthened its position as Finland’s leading product media company. The ownership change is intended to support Innoflame’s next phase of growth, including its ambition to build a significant European product media company with the capability to expand rapidly into new markets. The transaction is conditional to the customary closing conditions such as authority approvals. Innoflame is one of Finland’s leading product media specialists, helping its clients build a unified brand experience by offering the design, sourcing and management of product media as a single integrated service. Korona Invest is a Finnish private equity firm founded in 2006, specialising in buyout and growth investments in domestic small and medium-sized enterprises. It makes both majority and minority investments, structuring each project to suit the company’s growth strategy.
Case published 27.8.2026
Marina Group – Acquisition of Iisiveneily and Porvoon Venekorjaamo
We advised Hopeasalmen Telakka Oy, part of Marina Group, on the acquisitions of Iisiveneily and Porvoon Venekorjaamo. The transactions form part of Marina Group’s expansion into the Finnish marina and boatyard sector, strengthening its position under the Quattro Marine brand. Following the acquisitions, Quattro Marine’s Finnish operations comprise Hopeasalmen Telakka, which operates boatyard facilities in Helsinki’s Mustikkamaa and in Tolkkinen, Porvoo, together with Iisiveneily and Porvoon Venekorjaamo. Marina Group is a Norwegian marina and boatyard consortium owned by the private equity sponsor Norvestor. It has grown rapidly through acquisitions to become the Nordic region’s largest boating services provider, having acquired 24 marinas and boatyards across Norway, Sweden and Finland within roughly a year.
Case published 24.8.2026