At the turn of the year, we discussed how the Consumer Protection Act (38/1978, as amended) is entering the digital age following the implementation of the EU’s Sales of Goods Directive (2019/771) and the Digital Content and Digital Services Directive (2019/770) into national legislation (see here and here). Now, further amendments lie ahead when the so-called Omnibus Directive (2019/2161) is implemented into national legislation. The new provisions of the Consumer Protection Act will enter into force on 1 January 2023 in order to allow companies to prepare for the new requirements.
12.8.2022
New Amendments to the Consumer Protection Act in January 2023: National Implementation of the Omnibus Directive Leading to Major Changes for Businesses
Hilma-Karoliina Rozell & Piia Raappana
The Omnibus Directive aims to improve remedies for consumers, remove any shortcomings and inconsistencies of the provisions and lay down penalties in the event of infringements of certain directives. In this article, we will highlight the key amendments based on the Omnibus Directive of which businesses trading with consumers should be aware.
Reforms on price reduction announcements
Amendments to chapter 2 section 11 of the Consumer Protection Act will revise the regulation on price reduction announcements.
New extensions to the right of withdrawal in door-to-door selling
The new provision in chapter 6 of the Consumer Protection Act includes extensions to the consumers’ right of withdrawal in door-to-door selling. In this respect the regulation is purely national and not based on the Omnibus Directive.
Regulation on consumer reviews
The Omnibus Directive also affects the consumer reviews published by the businesses themselves.
1. provide fake consumer reviews or endorsements;
2. purchase reviews or endorsements;
3. misrepresent consumer reviews or social endorsements.
Information requirements for marketplace providers
The Consumer Protection Act will also include new information requirements for providers of online marketplaces. An ‘online marketplace’ means a virtual marketplace that allows consumers to conclude distance contracts with other consumers or businesses.
Compensation for damages caused by unfair marketing and practices
Following the Omnibus Directive, consumers may have the right to compensation for any damage caused by the business to the consumer by unfair marketing or unfair commercial practices. This kind of damage can, for example, include travel expenses incurred by the consumer. In addition, the consumer may be entitled to a reasonable price reduction if the trader has acted unfairly, for example by marketing aggressively or misleadingly.
Written confirmation procedure for telemarketing
Parliament has also accepted new legislation on telemarketing, which also enters into force on 1 January 2023. This national regulation is not based on the Omnibus Directive.
This regulation will include an obligation to implement a written confirmation procedure. In other words, after making an offer to a consumer during a call, telemarketers would, in principle, have to provide the consumer with the offer in a permanent form, for example as an email attachment. Unless the consumer accepts the offer in a permanent manner after the call, the contract is not binding on the consumer. Neglecting to use the confirmation procedure could result in penalty payments for the trader.
Latest news
Latest references
Cibus Real Estate – Acquisition of three retail properties
We advised Cibus Real Estate AB (publ) on its acquisition of three newly built retail properties in Pori, Finland. Kesko is the tenant in all three properties, and the average lease term is 8.1 years. Cibus is a real estate company listed on Nasdaq Stockholm Mid Cap. The company’s business concept is to acquire, develop and manage properties in Europe with daily goods chains as anchor tenants. The company currently owns approximately 700 properties in Europe.
Case published 12.11.2026
Seaya Nova and Molten Ventures – USD 80 million series C financing of Pliant
We advised Seaya Nova and Molten Ventures as Finnish counsel in connection with the USD 80 million Series C financing of Pliant, a Berlin-based fintech specialising in B2B payment solutions and corporate credit cards. The financing round was led by Seaya Nova and Speedinvest, with participation from Illuminate Financial, Motive Partners, Molten Ventures and Citi Ventures. Founded in Berlin in 2020, Pliant provides modular payment solutions for businesses and holds an EU e-money licence in Finland as well as a licence from the UK Financial Conduct Authority. We advised on the Finnish law aspects of the transaction alongside YPOG, which acted as lead counsel to Seaya Nova and Molten Ventures.
Case published 12.11.2026
Nala Renewables – Development, acquisition and financing of battery energy storage system (BESS) project
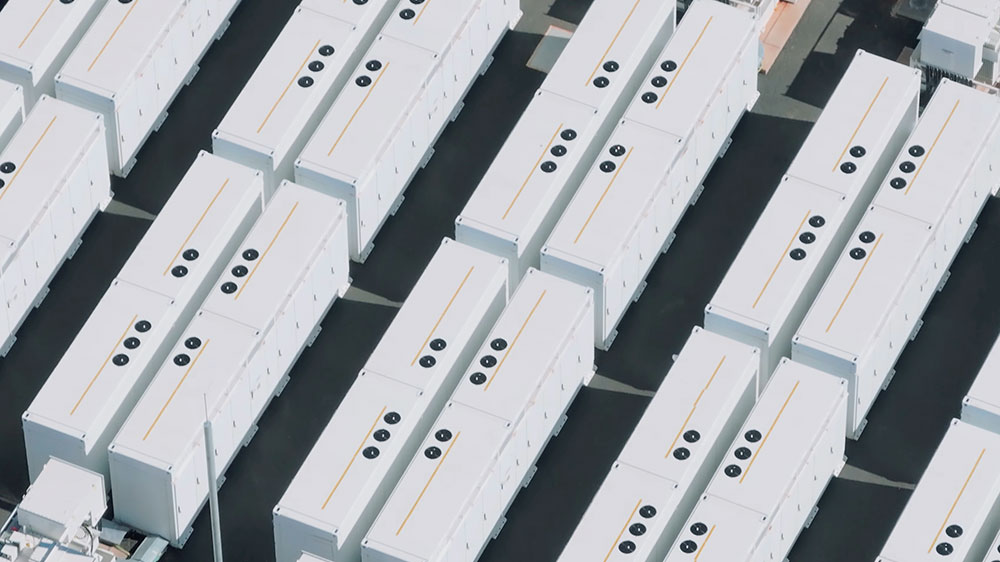
We advised Nala Renewables on the Finnish law aspects of the development, acquisition and financing of its battery energy storage system (BESS) project in Vuolijoki, Finland. The project comprises a 125 MW / 250 MWh battery energy storage system. Our advice extended beyond financing to the transaction’s legal due diligence and the acquisition of the project company. We also advised on key project contracts and financing documentation for the project finance facilities provided by Coöperatieve Rabobank U.A. The project is part of Nala Renewables’ growing portfolio of battery storage assets in Finland and the wider Nordic region, supporting the integration of renewable energy and contributing to the flexibility and stability of the Finnish electricity grid.
Case published 3.11.2026
Foundation Clinic – Funding Round
We advised Foundation Clinic in connection with its funding round backed by a group of prominent Finnish technology entrepreneurs and investors, including founders behind Supercell and Wolt. Foundation Clinic is a Finnish healthcare company developing a new approach to private healthcare focused on preventive, data-driven and continuous care. The company aims to combine comprehensive health data with ongoing medical care to identify and address health risks at an early stage.
Case published 29.10.2026