A few weeks ago, the Ministry of Finance published a draft bill for amendments to the right to deduct interest expenses. The proposal has some major issues that threaten to harm Finland’s competitiveness as a destination for international investments. Corporations and financial institutions will also find much to criticise in the proposal.
9.3.2018
Proposed Restrictions to Interest Deductions Would Harm Finland’s Competitiveness
Mikko Alakare
Related services
Bringing Finnish National Legislation up to the Minimum Level of the Directive
The proposed amendments are based on the EU’s Anti Tax Avoidance Directive (ATAD), which sets a minimum level for national legislation. However, the Ministry of Finance’s proposal goes significantly further than the ATAD requires. Finland should not implement more strict regulations than the minimum required level, because we don’t yet know how our key competitors are implementing the same directive – based on preliminary information, they are certainly not going as far as the Finnish proposal. Furthermore, Finland should take advantage of the wiggle room provided by the directive in order to secure our national competitiveness.
Tightening Rules for Interest Deduction
The minimum level required by the ATAD will already significantly tighten national interest deduction rules, but the Ministry of Finances proposal goes even further. In addition to restricting affiliated company interest deductions, the Ministry proposes restricting the deduction of interest expenses of loans from third parties. The Ministry’s proposal would expand the scope of restrictions to the point that they would catch, for example, companies in the real estate business and financial sector. The proposal also significantly expands definition of interest to cover various bank fees and advisory costs.
According to the proposal, the deductibility of interest expenses payable to third parties would only be restricted when the tax subject is part of a group or is associated with the other party or has a permanent establishment. It is odd, to say the least, that the legislator would take such a strong hand in guiding how companies arrange their own operations. If establishing a subsidiary or expanding operations abroad could poison a company’s existing bank financing, we can justifiably ask whether this kind of regulation is acceptable from the perspective of the right of domicile and equality.
As the current regulatory framework will be changing in any case, it is vital that the most problematic parts of the bill be addressed without delay. The new regulations will force tax subjects to reassess their financing and even their corporate structures, and it is vital that the final form of the amendments is clear as soon as possible. Due process requires that any amendments be known as soon as the tax year starts. The current proposed timetable is unacceptable for tax subjects whose 2019 tax year has already started.
In my opinion, at least the following changes should be made to the proposal:
Predictable tax treatment and flexible financing opportunities are decisive factors for international investors considering investments in Finland. Interest deduction provisions are a key part of tax treatment. As we don’t yet know what other countries are doing, it is completely unnecessary to harm Finland’s attractiveness by implementing the ATAD bin a more stringent form than international agreements require.
Latest insights
Article published 6.2.2026 – Tax & Structuring
Electricity sector Profit Tax Act in conflict with EU law – SAC denied leave to appeal
 Article published 14.1.2026 – Tax & Structuring
VAT deductions for private equity investors under the microscope
 Article published 16.12.2025 – Environment, Energy & Green Transition
Parliament approves substantial increases in tax on mined minerals
 Article published 25.6.2025 – Tax & Structuring
Administrative Court ruling: the Profit Tax Act targeting electricity companies is in conflict with EU law

Janne Juusela & Mikko Alakare
Mikko Alakare & Lotta Manu
Tarja Pirinen, Mikko Alakare & Noora Ahonen
Janne Juusela, Mikko Alakare, Samuli Tarkiainen, Anette Sainio, Noora Ahonen & Joakim Nivala
Latest references
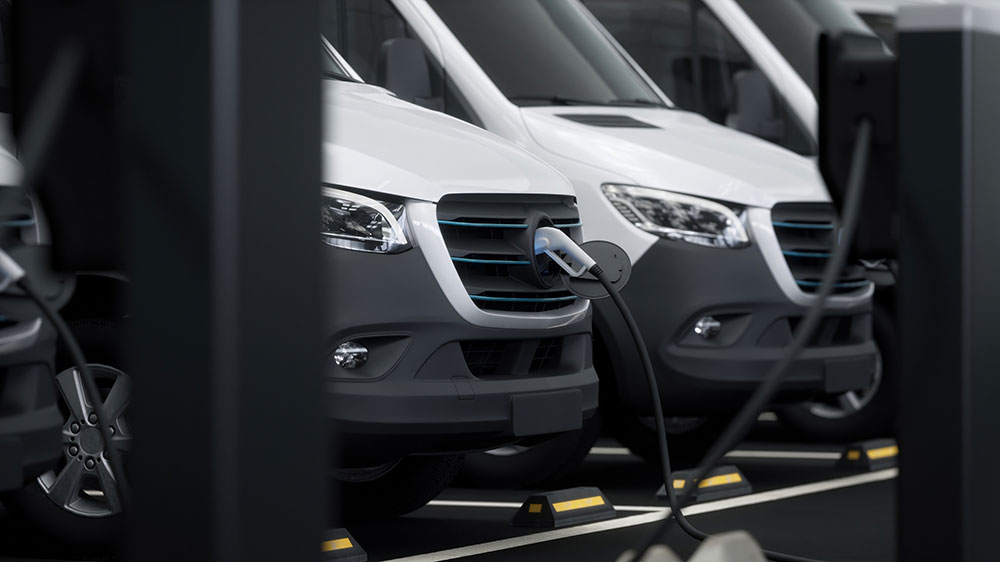
Jolt Capital and Tesi – Investment in VEV
We advised Jolt Capital and Tesi in connection with their investment in VEV, a leading provider of commercial fleet electrification solutions. The investment, led by Jolt Capital with Tesi as co-investor, will support VEV’s next phase of growth and expansion across Europe. As part of the transaction, VEV became an independent company following the acquisition of Vitol’s stake in the business. Founded by Vitol, VEV provides integrated fleet electrification solutions combining fleet strategy, charging infrastructure, energy supply and operational services. Through its VEV IQ platform, the company supports more than 6,000 commercial electric vehicles across Europe and has been deployed across more than 600 sites spanning the transport, logistics and waste sectors. Jolt Capital is a private equity firm focused on growth investments in European deeptech companies. Tesi is a Finnish state-owned investment company that promotes Finnish business and economic growth through investments. We advised Jolt Capital and Tesi on the equity financing and structuring aspects of the transaction. International law firm Goodwin advised the investors on the acquisition of VEV.
Case published 10.9.2026
HANZA – Divestment of its Nivala and Sievi operations
We advised HANZA on the divestment of its Nivala and Sievi operations. The transaction was part of HANZA’s larger strategic reorganisation, where the company optimised its Finnish manufacturing cluster. Founded in 2008, HANZA is a Swedish mechanical engineering and electronics contract manufacturing company listed on the Nasdaq Stockholm main list. HANZA has approximately 5,000 employees and annual sales of SEK 10 billion.
Case published 3.9.2026
Kiwa – Acquisition of Sertio
We advised Kiwa in its acquisition of Sertio Oy, a Finnish notified body designated by the authority in accordance with the EU Regulation on in vitro diagnostic medical devices (IVDR). Sertio provides conformity assessment services in accordance with IVDR. Kiwa is one of the world’s leading testing, inspection, and certification companies, operating in over 35 countries.
Case published 7.5.2026

Metsäkonepalvelu – Acquisition of Junnonen Forest and the business operations of Lamerit
We advised Metsäkonepalvelu Oy in its acquisition of the entire share capital of Junnonen Forest Oy, a Finnish timber harvesting services company, and the timber harvesting services business of Lamerit Oy. The acquisition supports Metsäkonepalvelu’s growth strategy and strengthens the company’s position, particularly in southeastern Finland. Metsäkonepalvelu is a portfolio company of A. Ahlström Oy, a Finnish family-owned industrial owner. The company provides mechanical timber harvesting services to forest companies, large private forest owners, and the public sector in Finland and Sweden. Metsäkonepalvelu Group employs nearly two hundred forestry professionals.
Case published 6.5.2026