The Finnish Ministry of Finance published a proposal on amendments to Finnish controlled foreign corporations (CFC) legislation in the beginning of August 2018. The ministry also stated that the Finnish anti-avoidance regulation would remain in its existing form. Finnish tax regulations concerning CFCs are being reformed as a part of the EU’s anti tax avoidance directive (Council Directive (EU) 2016/1164 of 12 July 2016, ATAD).
13.8.2018
Fundamental Changes to Finnish CFC Legislation Expected
Jenni Korhonen & Mikko Alakare
Related services
Tags
The purpose of existing Finnish CFC legislation is to prevent tax planning by utilizing entities located in low-tax jurisdictions where the actual level of taxation is less than 60% of the taxation of a Finnish entity.
The existing rules are already relatively complex, but contain key exemptions on which domestic taxpayers could have relied.
The most essential proposed changes relate to the applicability of the key exemptions and the calculation methods of required ownership levels. These amendments are briefly discussed below.
Definition of a CFC and Exemptions
Finnish CFC regulations include commonly utilised exemptions. The current exemptions may apply to, for example, CFCs mainly receiving their profits from industrial production activities, corresponding other production activities, shipping activities, or sales or marketing activities that serve the above activities and are allocated to that geographical area.
Another currently applicable major exemption relates to situations when the relevant foreign entity is i) de facto resident in another European Economic Area (EEA) member state, or ii) de facto resident in a country that does not e.g. belong to the list of low-tax jurisdictions issued by Finnish Ministry of Finance and has a double tax convention in force with Finland, and the foreign entity i.a. factually pursues economic activity in that country or has not received any specific tax exemptions.
According to the proposal, the first exemption would in a slightly expanded form continue to apply to companies resident outside the EEA alongside certain other requirements, whereas Finnish tax residents could utilise the latter exception in the case of companies in the EEA but no longer in the case of companies that are tax resident outside the EEA. As the scope of the exemptions will change, several foreign companies may fall out of the exemption currently applied.
The ATAD also includes certain de minimis thresholds regarding, for example, transaction types or accounting profit levels. However, the new domestic proposal contains no such exceptions.
Calculation of Ownership Thresholds
Current CFC regulations are applicable only if one or more Finnish tax resident entities or individuals directly or indirectly hold at least 50% of the capital or votes of a CFC or have the right to at least 50% of the profit of the CFC. This test would be abolished in the new proposed regulation.
In addition, a Finnish tax resident entity or individual is currently in scope of CFC legislation only if it directly or indirectly by itself or together with dependent entities holds at least 25% of capital of the CFC or is entitled to 25% of profit from its assets.
According to the new proposal, the calculation would also take into account direct or indirect holdings in the CFC by Finnish and non-Finnish dependent entities. This means in practice that Finnish taxpayers with only minor direct or indirect ownership in a CFC may become subject to observe CFC regulation.
Other Remarks
The ATAD excludes individuals from the scope of CFC regulation, though both the existing and planned new domestic regulation would also concern them. This has been a problem already under the existing rules, as the determination and application of CFC legislation may in practice be overly complex for individuals that are, for example, indirect passive owners in foreign entities. This problem would become even more evident under the new regulation.
In addition, the new rules would include an amendment concerning the sale of shares in a CFC. In that case, the income taxed as CFC income at the hands of the taxpayer during previous years could be taken into account when determining tax consequences of the taxable disposal.
Conclusions
As stated above, the existing CFC rules are complex. The new proposal would do nothing to decrease the degree of complexity. Further, the Finnish CFC system would structurally deviate from CFC regulations of several other EU member states that have implemented either of the models provided by ATAD.
Secondly, the amended CFC rules would bring several new foreign entities under the scope of Finnish CFC regulations due to amended ownership thresholds and modifications to current exemptions. The effect could be especially relevant for directly or indirectly held companies operating in a tax treaty country outside the EEA and not currently benefitting from industry-based exemptions.
No Amendments to Finnish Anti-Avoidance Regulation
Another topic discussed by the Ministry of Finance was the anti-avoidance provisions. Anti-avoidance provisions were also subject to evaluation by implementation of ATAD.
The Ministry of Finance ended up suggesting that the existing anti-avoidance provisions stay in their current form. The contents of the current domestic anti-avoidance provisions are deemed to be at least as strict as the minimum level regulations provided by ATAD.
Future Steps
The proposal for the new regulation regarding both CFC provisions and anti-avoidance regulation is currently being circulated for comments. The final version of the renewed provisions will be published during autumn 2018. New provisions will be applicable in taxation for 2019.
Latest news
Latest references
Efima – Sale of AI business
We advised Efima Oyj on the sale of its AI business to Better Care Technologies Oy. The transaction included Efima’s Moiva AI platform developed for the care sector, the related technology and brand, customer contracts, and the experts working in the business. Efima is a Finnish digital company that supports the sustainable growth of large and mid-sized companies by streamlining their business processes and by creating competitive advantage through the innovative use of artificial intelligence and data. The company has nearly 200 experts based in Helsinki and Tampere.
Case published 21.9.2026
Neoen – Sale of data centre
We advised Neoen Renewables Finland Oy, part of the French Neoen Group, in its sale of a data centre project to a consortium consisting of international data centre developers and operators. This marked Neoen’s first data centre development project in Finland. Founded in 2008, Neoen is one of the world’s leading independent renewable energy producers. The company operates in 15 countries. It develops, finances, builds, owns, and operates solar power plants, wind farms, and battery storage systems. Neoen Group is owned by global alternative asset manager Brookfield Corporation.
Case published 17.9.2026
Jolt Capital and Tesi – Investment in VEV
We advised Jolt Capital and Tesi in connection with their investment in VEV, a leading provider of commercial fleet electrification solutions. The investment, led by Jolt Capital with Tesi as co-investor, will support VEV’s next phase of growth and expansion across Europe. As part of the transaction, VEV became an independent company following the acquisition of Vitol’s stake in the business. Founded by Vitol, VEV provides integrated fleet electrification solutions combining fleet strategy, charging infrastructure, energy supply and operational services. Through its VEV IQ platform, the company supports more than 6,000 commercial electric vehicles across Europe and has been deployed across more than 600 sites spanning the transport, logistics and waste sectors. Jolt Capital is a private equity firm focused on growth investments in European deeptech companies. Tesi is a Finnish state-owned investment company that promotes Finnish business and economic growth through investments. We advised Jolt Capital and Tesi on the equity financing and structuring aspects of the transaction. International law firm Goodwin advised the investors on the acquisition of VEV.
Case published 10.9.2026
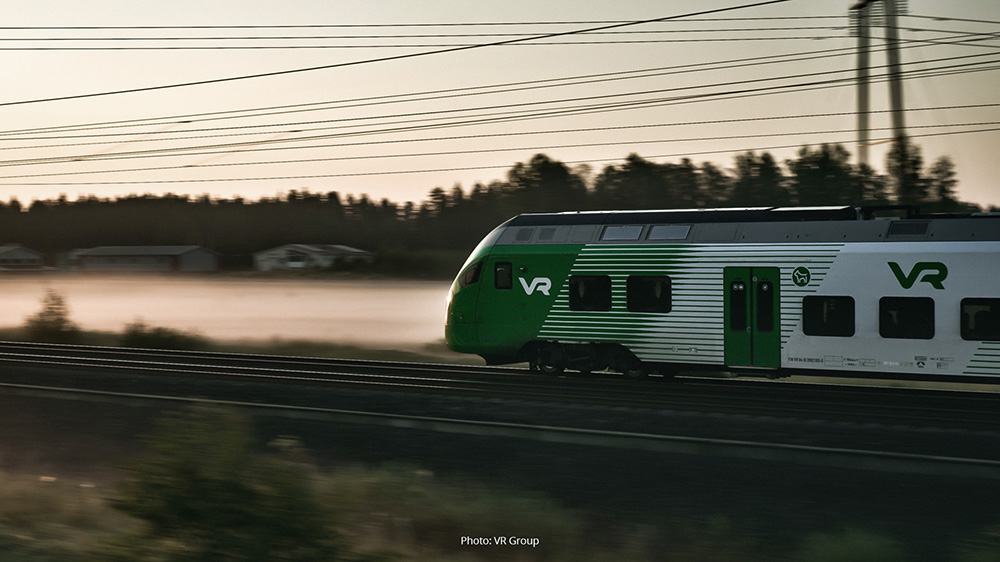
VR Group – Intellectual property matters
VR-Group Plc is a transport and logistics group owned by the Finnish State, operating passenger and freight rail transport in Finland with activities also in the Swedish market. VR Group provides passenger, logistics and maintenance services with over 160 years’ experience in developing responsible transport of the future. We advise VR Group in intellectual property matters as part of the company’s wider brand protection efforts. Our assignments have included advice on copyright, design rights and trademarks, focusing on the protection of the company’s visual identity – including its distinctive green colour – in connection with transport services as part of a comprehensive IP protection strategy. VR Group’s consistent brand building has also received recognition, including the Finland Chamber of Commerce’s Brand of the Year award in 2026. In the competition, brands were viewed comprehensively from various perspectives, including their story, strategic role, brand renewal ability and intellectual property protection. The jury found that VR had understood the importance of the protection of its brand as part of a comprehensive business strategy.
Case published 9.9.2026