In September 2023, the European Commission published its proposed directive on Business in Europe: Framework for Income Taxation (BEFIT) aimed at cross-border groups. The proposed directive includes a common set of rules to determine the tax base of companies belonging to the same group within the EU, with the purpose of aggregating the tax bases into one single tax base. Once the aggregated tax base has been determined, each group company will be assigned a percentage of the aggregated tax base. This percentage will be based on the average of the taxable results in the previous three fiscal years.
9.10.2023
The European Commission proposes changes to transfer pricing and the taxation of large international groups within the EU
Janne Juusela, Mikko Alakare & Noora Ahonen
Related services
In the same connection, the Commission issued a separate proposal for harmonising transfer pricing rules within the EU. This proposal aims at enhancing tax certainty and, consequently, reducing tax litigation and double-taxation. Moreover, it also aims at reducing aggressive tax planning schemes.
The proposed directive would concern large groups that are subject to EU regulations
The BEFIT Directive will be mandatory only for groups operating in the EU with a combined revenue of at least EUR 750 million over a certain period, and where the ultimate parent entity hold at least 75% of the ownership rights or of the rights giving entitlement to profit. Another precondition is that the group companies prepare consolidated financial statements. Groups with a lower revenue operating in the EU may also choose to opt in as long as they prepare consolidated financial statements.
The proposed regulation may initially lead to additional work
The proposed directive is another step towards a common EU corporate taxation system and the plan for a common allocation method in which the results, determined under common rules, would be allocated for taxation in the group companies’ home countries using a formulary apportionment. The proposed regulation aims to further develop the EU’s internal market and reduce the procedural costs caused by applying multiple taxation frameworks. It is also expected to encourage cross-border investments within the EU. While the Commission predicts that the regulation could result in significant savings in procedural costs, the implementation and application of the new regulation will likely lead to additional work for groups, at least in the initial stage. The situation is further complicated by the fact that the proposed directive only concerns companies that fall under EU regulation. In other words, it does not apply to cases in which a company’s tax residence is in a non-EU state.
The contents of the directive are not yet set in stone
The BEFIT Directive is proposed to enter into force on 1 July 2028. If the transfer pricing proposal proceeds as planned, it would enter into force on 1 January 2026 already. However, the directives must first pass through the hands of the European Parliament and of the Council. The proposed regulation and the allocation of revenue concern the taxing rights of Member States, which have traditionally been difficult questions on the EU level. It is therefore highly uncertain that the European Parliament and the Council would adopt the proposed regulations, at least exactly as proposed. Nevertheless, it is necessary to renew the international corporate taxation system, and we are bound to see some changes sooner or later.
Latest news
Latest references
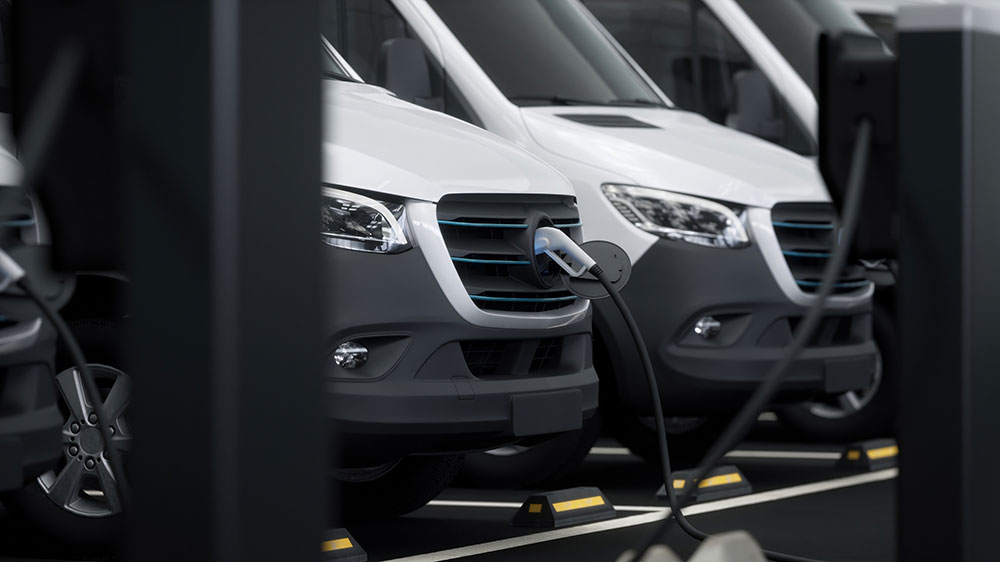
Jolt Capital and Tesi – Investment in VEV
We advised Jolt Capital and Tesi in connection with their investment in VEV, a leading provider of commercial fleet electrification solutions. The investment, led by Jolt Capital with Tesi as co-investor, will support VEV’s next phase of growth and expansion across Europe. As part of the transaction, VEV became an independent company following the acquisition of Vitol’s stake in the business. Founded by Vitol, VEV provides integrated fleet electrification solutions combining fleet strategy, charging infrastructure, energy supply and operational services. Through its VEV IQ platform, the company supports more than 6,000 commercial electric vehicles across Europe and has been deployed across more than 600 sites spanning the transport, logistics and waste sectors. Jolt Capital is a private equity firm focused on growth investments in European deeptech companies. Tesi is a Finnish state-owned investment company that promotes Finnish business and economic growth through investments. We advised Jolt Capital and Tesi on the equity financing and structuring aspects of the transaction. International law firm Goodwin advised the investors on the acquisition of VEV.
Case published 10.9.2026
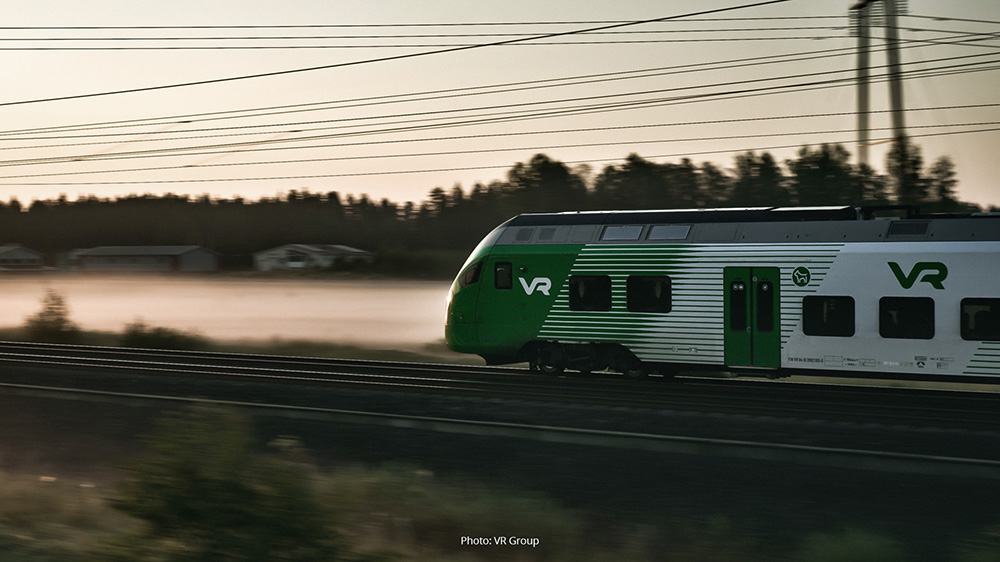
VR Group – Intellectual property matters
VR-Group Plc is a transport and logistics group owned by the Finnish State, operating passenger and freight rail transport in Finland with activities also in the Swedish market. VR Group provides passenger, logistics and maintenance services with over 160 years’ experience in developing responsible transport of the future. We advise VR Group in intellectual property matters as part of the company’s wider brand protection efforts. Our assignments have included advice on copyright, design rights and trademarks, focusing on the protection of the company’s visual identity – including its distinctive green colour – in connection with transport services as part of a comprehensive IP protection strategy. VR Group’s consistent brand building has also received recognition, including the Finland Chamber of Commerce’s Brand of the Year award in 2026. In the competition, brands were viewed comprehensively from various perspectives, including their story, strategic role, brand renewal ability and intellectual property protection. The jury found that VR had understood the importance of the protection of its brand as part of a comprehensive business strategy.
Case published 9.9.2026
NoHo Partners – EUR 50 million secured notes and EUR 97 million senior secured facilities agreement
We advised NoHo Partners Plc on the issuance of EUR 50 million senior secured floating rate notes. The notes have a tenor of four years and mature on 10 September 2030. The notes bear interest at a rate of three-month EURIBOR plus a margin of 4.375 per cent. per annum. The notes were allocated to a mix of domestic and international investors. We also advised NoHo Partners on the negotiation of its new senior facilities agreement. The facilities agreement comprises a EUR 60,000,000 term loan facility, a EUR 10,000,000 capex facility and a EUR 27,000,000 revolving credit facility. “We are delighted by the interest investors have shown in the company’s Notes, which reflects confidence in our strategy. The successful issuance of the Notes, together with the new loan agreement, extends the maturity profile of our financing and enables the company to continue executing its growth strategy going forward. I would like to thank all investors for their participation, as well as our partner bank for the excellent execution of the Notes issuance”, says Jarno Suominen, CEO of NoHo Partners. OP Corporate Bank plc acted as the sole lead manager and bookrunner for the issue of the notes. NoHo Partners Plc is a Finnish group established in 1996, and it specialises in restaurant services being the creative innovator of the Northern European restaurant market. The company was listed in Nasdaq Helsinki in 2013 becoming the first Finnish listed restaurant company, and it has continued to grow strongly throughout its history. NoHo Partners’ vision is to be the leading restaurant operator in Northern Europe.
Case published 4.9.2026
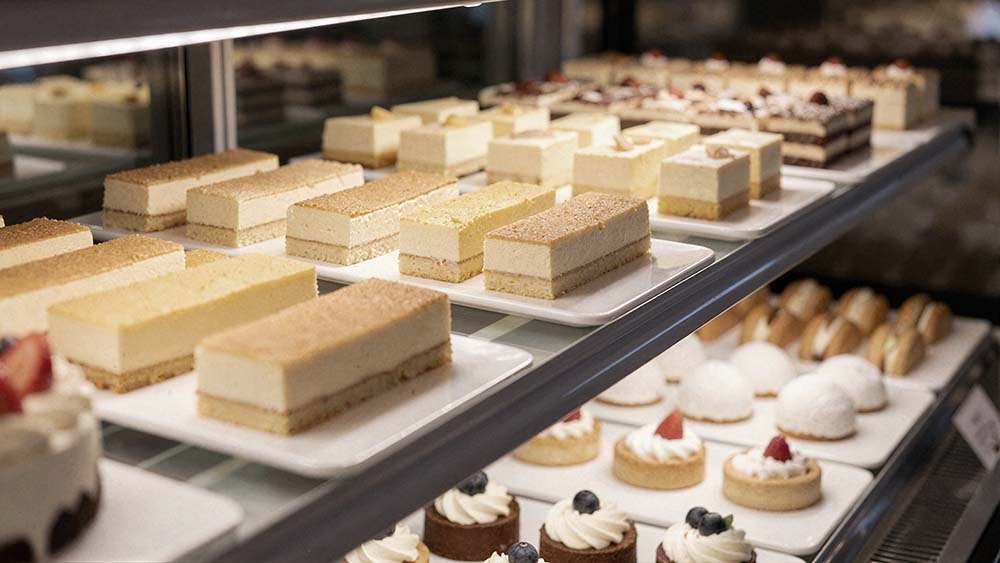
Topfoods – Acquisition of Delice Plus
We advised Topfoods Oy, a Triton-backed Geia Group company, on its acquisition of Oy Delice Plus Ab, a Finnish supplier of cakes and pastries. Through the acquisition, Topfoods strengthens its retail business and further reinforces its position in the cakes and pastries segment. Founded in 2008, Topfoods supplies selected food products to professional kitchens, the retail sector, and the food industry.
Case published 4.9.2026