In September 2025, the Supreme Administrative Court (SAC) issued a landmark decision KHO 2025:61, which partially revised the interpretative guidelines on the VAT deductibility of transaction costs, particularly in transactions led by private equity investors.
14.1.2026
VAT deductions for private equity investors under the microscope
Mikko Alakare & Lotta Manu
Related services
While the decision clarified certain principles, it is also problematic, imposing a strict burden of proof on companies regarding the allocation of costs. A particular risk for private equity investors is that transaction costs could be allocated to them retroactively, with no right to deduct VAT due to the nature of their business. In the absence of more precise guidance, companies cannot be certain they will have the right to deduct VAT without seeking a preliminary ruling, and retrospective adjustment carries a significant risk of tax penalties.
Past practice
Earlier tax practice has already made it clear that if services purchased in connection with a transaction only benefit the acquiring company indirectly, that company cannot deduct the VAT on the services. Instead, the costs should be allocated to the company that directly benefits from the services. Examples of such services provided in the interest of investors include shareholders’ agreements concerning the owners of the acquiring company and planning services for the upper-tier acquisition structure.
Three deduction categories and allocation of costs
The SAC decision classifies professional services into three categories based on deductibility: fully deductible, partially deductible and non-deductible. This means that some professional services may be only partially deductible for the acquiring company, and the rest should be allocated to, for example, investors higher up in the acquisition structure. According to the SAC, such partially deductible costs – i.e. costs related to services that partially benefit investors – may include, for example, due diligence costs. The SAC did not take a more detailed position on how the costs should be allocated between the companies.
Lack of guidance
For the time being, the Tax Administration has not provided detailed guidance on the allocation of costs, which means that companies must make their own assessments based on the general principles set out by the SAC. This is a challenging situation, as the allocation can create a substantial administrative burden for taxpayers and require significant manual work. Especially in the case of larger transactions, it is advisable to discuss the cost allocation in advance with the Tax Administration and apply for a preliminary ruling when necessary. In a panel discussion on the subject held in December, the Tax Administration indicated that it would cooperate with taxpayers on the matter and was open to more informal discussions to find solutions.
Documentation
Going forward, documenting costs will be particularly important, and companies will also need to ensure that the content of the services can be verified retrospectively. This is necessary to determine who benefitted from the services purchased in connection with the transaction – or in other words, who has the right to deduct VAT on these purchases. The company must be able to justify the allocation used for tax deductions. In the individual case now decided by the SAC, for example, the provisions in the shareholders’ agreement regarding costs took on unexpected significance, indicating that such provisions should be drafted with particular care. With clearer documentation, the outcome of the decision could have been more straightforward and perhaps even different to some extent.
The situation may not be as problematic as initially feared after the SAC issued its decision. With careful documentation, companies and investors can prepare for any upcoming Tax Administration investigations already when structuring the transaction. Our discussions with the Tax Administration indicate that they are open to dialogue with companies and their advisors.
– Mikko Alakare
Key considerations for private equity investors
- Correct allocation: Ensure that costs are allocated and, if necessary, recharged to the company to whose business they are directly and immediately related. The acquiring company may not be entitled to fully deduct VAT on professional services charged in connection with the transaction.
- Sufficient documentation: Be prepared to clarify and prove that the costs were allocated to the correct company. Make sure that the documentation is clear enough to be understood even a few years later, and require advisors to provide detailed invoice itemisation for their work.
C&S experts have advised clients on a number of assignments related to transaction cost VAT deductions even before the latest SAC precedent. We are available to assist you with any investigations and processes on the subject.
Latest insights
Article published 6.2.2026 – Tax & Structuring
Electricity sector Profit Tax Act in conflict with EU law – SAC denied leave to appeal
 Article published 16.12.2025 – Environment, Energy & Green Transition
Parliament approves substantial increases in tax on mined minerals
 Article published 25.6.2025 – Tax & Structuring
Administrative Court ruling: the Profit Tax Act targeting electricity companies is in conflict with EU law
 Article published 7.4.2025 – Private Equity
Tax credit for major clean transition investments passed in Parliament – application period until 29 August 2025


Janne Juusela & Mikko Alakare
Tarja Pirinen, Mikko Alakare & Noora Ahonen
Janne Juusela, Mikko Alakare, Samuli Tarkiainen, Anette Sainio, Noora Ahonen & Joakim Nivala
Janne Juusela, Mikko Alakare, Samuli Tarkiainen, Marius af Schultén, Jarno Tanhuanpää, Kanerva Sunila & Noora Ahonen
Latest references
Jolt Capital and Tesi – Investment in VEV
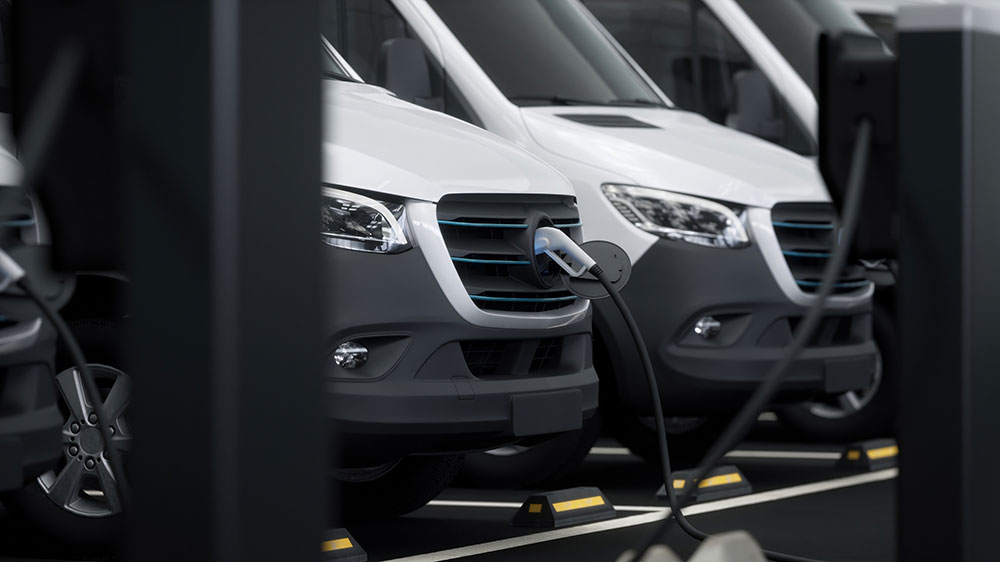
We advised Jolt Capital and Tesi in connection with their investment in VEV, a leading provider of commercial fleet electrification solutions. The investment, led by Jolt Capital with Tesi as co-investor, will support VEV’s next phase of growth and expansion across Europe. As part of the transaction, VEV became an independent company following the acquisition of Vitol’s stake in the business. Founded by Vitol, VEV provides integrated fleet electrification solutions combining fleet strategy, charging infrastructure, energy supply and operational services. Through its VEV IQ platform, the company supports more than 6,000 commercial electric vehicles across Europe and has been deployed across more than 600 sites spanning the transport, logistics and waste sectors. Jolt Capital is a private equity firm focused on growth investments in European deeptech companies. Tesi is a Finnish state-owned investment company that promotes Finnish business and economic growth through investments. We advised Jolt Capital and Tesi on the equity financing and structuring aspects of the transaction. International law firm Goodwin advised the investors on the acquisition of VEV.
Case published 10.9.2026
HANZA – Divestment of its Nivala and Sievi operations
We advised HANZA on the divestment of its Nivala and Sievi operations. The transaction was part of HANZA’s larger strategic reorganisation, where the company optimised its Finnish manufacturing cluster. Founded in 2008, HANZA is a Swedish mechanical engineering and electronics contract manufacturing company listed on the Nasdaq Stockholm main list. HANZA has approximately 5,000 employees and annual sales of SEK 10 billion.
Case published 3.9.2026
Kiwa – Acquisition of Sertio
We advised Kiwa in its acquisition of Sertio Oy, a Finnish notified body designated by the authority in accordance with the EU Regulation on in vitro diagnostic medical devices (IVDR). Sertio provides conformity assessment services in accordance with IVDR. Kiwa is one of the world’s leading testing, inspection, and certification companies, operating in over 35 countries.
Case published 7.5.2026

Metsäkonepalvelu – Acquisition of Junnonen Forest and the business operations of Lamerit
We advised Metsäkonepalvelu Oy in its acquisition of the entire share capital of Junnonen Forest Oy, a Finnish timber harvesting services company, and the timber harvesting services business of Lamerit Oy. The acquisition supports Metsäkonepalvelu’s growth strategy and strengthens the company’s position, particularly in southeastern Finland. Metsäkonepalvelu is a portfolio company of A. Ahlström Oy, a Finnish family-owned industrial owner. The company provides mechanical timber harvesting services to forest companies, large private forest owners, and the public sector in Finland and Sweden. Metsäkonepalvelu Group employs nearly two hundred forestry professionals.
Case published 6.5.2026