In October 2026, the Finnish Government submitted a proposal for a new act on the screening and authorisation of foreign investments (the FDI Act). The new FDI Act would replace the current act on the screening of foreign corporate acquisitions (172/2012) and, at the same time, implement the amendments required by Regulation (EU) 2026/1386 on the screening of foreign investments.
26.10.2026
Reform of Finnish FDI screening moves forward: significant changes and broader scope
Kiti Karvinen, Joachim Wik & Johanna Kyllöinen
Related services
The new FDI Act is intended to enter into force on 1 April 2027. The previous act will apply to investments made and pending before the entry into force of the new FDI Act.
Mandatory prior authorisation applies to all foreign investors
Under the new FDI Act, all persons other than Finnish citizens and all entities registered outside Finland would be considered foreign investors, meaning that investors located in the EU and EFTA countries would also fall fully within the scope of FDI screening. A company registered in Finland would also be considered a foreign investor if a foreign investor directly or indirectly holds at least 10% of the voting rights in that company or otherwise has actual influence over it.
With regard to private equity investors, the government proposal specifies that prior authorisation is not required if the investing fund is established or registered in an EU Member State and the ultimate control is exercised by non-foreign investors. Thus, investments made by a Finnish private equity investor are covered by the exemption if the ultimate control rests in Finland and no individual foreign investor have at least 10% of the voting rights or equivalent influence in the structure.
All investments within the scope of the new FDI Act would require prior authorisation if the thresholds (10%, 33.3%, 50%, 66.6% or 90%) are exceeded. The current voluntary notification procedure would be abolished and in the future all investments within the scope are subject to mandatory prior authorisation. Failure to comply with the mandatory prior authorisation may result in a significant administrative penalty payment (up to EUR 10 million or 10% of total global turnover for the previous financial year, whichever is greater), or the investment may be declared null and void and ordered to be unwound if the authority’s request to apply for the authorisation is not complied with.
The authorisation procedure will be two-phased in the future. The Finnish National Emergency Supply Agency (NESA, in Finnish Huoltovarmuuskeskus) will act as the authority for Phase I and needs to handle the matter within 45 calendar days. If the security implications of the investment cannot be ruled out in Phase I, the matter would then proceed to Phase II, which would be handled by the Ministry of Economic Affairs and Employment. No fixed deadline would apply to Phase II.
The authorisation must be granted unless the investment is deemed to endanger national security, military national defence, security of supply, other vital functions of society, foreign and security policy objectives, or public order or security, and conditions may be imposed on the authorisation to prevent or reduce risks if necessary.
The scope widens to numerous new sectors, including critical infrastructure, data centres, energy, and strategic raw materials
The sectors subject to the mandatory authorisation procedure would be defined more precisely in the new FDI Act. Prior authorisation applies to companies and businesses registered in Finland (excluding branches), and the Act applies to economic activities carried out in Finland and in the Finnish economic zone.
Companies producing or supplying defence products or products and services important to the defence industry, as well as companies manufacturing, developing or utilising dual-use goods, would continue to be subject to screening, as would companies supplying critical products or services to authorities.
The scope of the FDI Act would also cover companies whose activities involve access to classified information or information otherwise relevant to national security, as well as companies providing ICT or information security products or services relevant to national security or the security of supply.
Companies previously within the scope of the voluntary notification procedure would be subject to the mandatory authorisation procedure in the future. Companies whose operations relate to the security of supply, critical infrastructure, or other vital functions of society would also be subject to screening. These include, among others, the national rail network, roads, the airport network, ports, significant logistics terminals, information and communication networks, power plants, energy networks, data centres, production facilities in the food, chemical and metal industries, as well as water, electricity, heating and waste management services.
In addition, screening would extend to sectors within the scope of the EU Regulation, such as critical technologies (semiconductors, quantum technology, artificial intelligence), key functions in the transport, energy and digital infrastructure sectors, strategic raw materials, and electoral, financial and payment systems.
Greenfield investments subject to screening
Greenfield investments creating new business operations in Finland or in the Finnish economic zone would in future be within the scope of screening. A greenfield investment may be carried out, for example, by establishing a new company or business unit intended to carry on business activities within the meaning of the FDI Act. The acquisition of a previously established company that does not yet have actual business operations is also considered a greenfield investment if the purpose of the acquisition is to commence operations in a sector subject to screening.
Screening would cover, among others, projects in the defence sector and the production and development of dual-use goods. Going forward, screening would extend to situations where a company, business unit or entity to be established intends, for example, to produce or supply defence products or other products or services important to military national defence or the defence industry, or to manufacture or develop dual-use goods subject to export control authorisation.
Greenfield projects relating to infrastructure critical to society, such as projects relating to port and airport infrastructure and logistics terminals critical to the security of supply, would fall within scope. This category includes projects where the company to be established intends to construct or maintain port infrastructure, or to provide port operation and cargo handling services, to construct or maintain airport infrastructure or to provide ground handling services, or to establish a logistics terminal serving the food, healthcare, fuel, gas and hydrogen sectors or the needs of national defence and the defence industry.
Energy projects would also fall within the scope of screening going forward, as wind or solar power projects with an electric power of at least 300 MW, other electricity production or storage projects with an electric power of at least 100 MW, hydrogen production projects with an output of at least two tonnes per hour, and district heating or cooling production projects with an output of at least 100 MW would be subject to screening. The scope would also cover extraction, processing, recycling or utilisation activities relating to the EU’s strategic raw materials.
In addition to those already mentioned, data centres with a capacity of at least 100 MW would also be within the scope of screening where the activities involve matters sensitive in terms of security, security of supply or critical infrastructure.
What Finland’s FDI reform means for investors
The changes will increase the number of FDI applications in Finland, as the scope of both investors and sectors covered is significantly broadened and greenfield projects are also brought within the authorisation procedure.
Going forward, investors located in the EU and EFTA area will also need to apply for prior authorisation when investing in companies operating in sectors within the scope of the FDI Act or when undertaking a greenfield project in such a sector. The introduction of a 45-day handling time is a welcome reform for the purposes of planning a transaction timetable, as it increases predictability.
Parliamentary consideration of the new FDI act is still ongoing. The Act is intended to enter into force on 1 April 2027.
Latest insights
Article published 30.3.2026 – Competition & Procurement
Finnish FDI screening under reform — Update following the stakeholder consultation
Article published 9.7.2025 – FDI Regulatory Service
Defence sector investments and acquisitions – key facts about the Finnish FDI regulation
 Article published 10.3.2025 – Private M&A
Navigating uncharted waters: M&A and defence tech in the age of geopolitical uncertainty
Article published 27.1.2023 – Private Equity
The ability to carry out complex transactions brings competitive advantage
Kiti Karvinen, Johanna Kyllöinen & Joachim Wik
Kiti Karvinen & Markus Rahnu
Markus Rahnu
Karlo Siirala, Carola Lindholm & Jussi Nieminen
Latest references
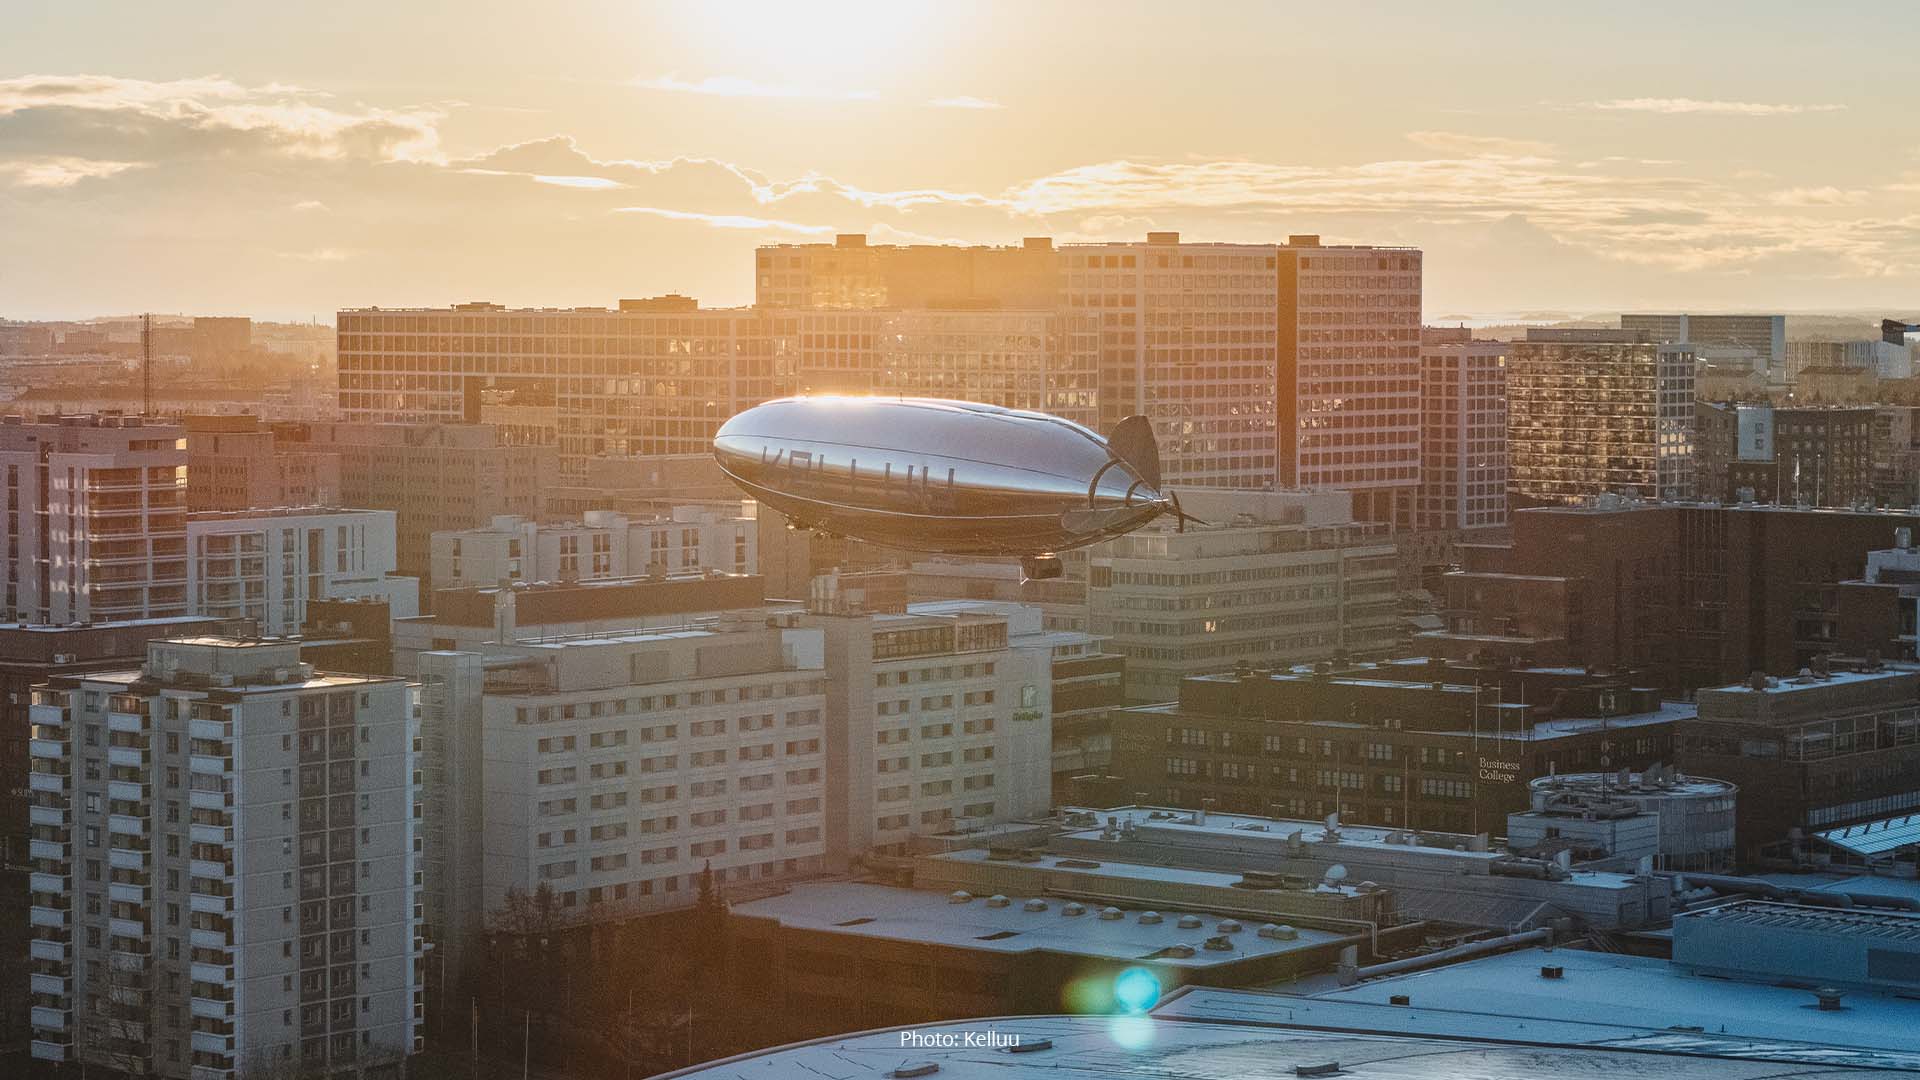
NATO Innovation Fund – Kelluu’s EUR 15 million Series A funding round
We advised the NATO Innovation Fund as lead investor on Kelluu’s EUR 15 million Series A funding round, with participation from Keen Venture Partners, Gungnir Capital, and Tesi. Kelluu is a Finnish deep tech company operating the world’s largest autonomous airship fleet. We advised NIF on this transaction alongside global law firm Latham & Watkins.
Case published 17.4.2026

KKR – Acquisition of Karo Healthcare
We acted as Finnish legal adviser to KKR in connection with its acquisition of the entire share capital of Karo Healthcare from EQT. The transaction follows Karo’s significant strategic transformation from a Nordic specialty pharma business into a leading pan-European consumer healthcare platform, with an attractive product portfolio spanning core categories such as Skin Health, Foot Health, and Intimate Health, as well as Digestive Health and Vitamins, Minerals & Supplements. KKR & Co. Inc. (NYSE: KKR), is a leading global investment firm that offers alternative asset management as well as capital markets and insurance solutions. KKR sponsors investment funds that invest in private equity, credit and real assets and has strategic partners that manage hedge funds. Completion of the transaction is subject to customary conditions and regulatory approvals. The transaction is expected to close in the coming months.
Case published 17.4.2025

WithSecure – Sale of open source data collection product and business
We advised WithSecure Oyj in the sale of its open source data collection product and business to Patria Oyj. The divested business combining software and services falls outside WithSecure’s current strategy. Through the sale, WithSecure sharpens its focus on the Elements portfolio. WithSecure is a global cyber security company (listed on NASDAQ OMX Helsinki) with more than 35 years of industry experience. WithSecure offers partners flexible commercial models, ensuring mutual success across the dynamic cyber security landscape. Patria is an international company in the defence and security industry offering defence, security and aviation life cycle support services and technology solutions. As a result of the transaction, Patria will open a new office in Oulu and 10 WithSecure experts currently working in the business area will join Patria.
Case published 30.9.2024
Mérieux Equity Partners – Acquisition of Labquality
We acted as the legal and ESG advisor to Mérieux Equity Partners on the acquisition of a majority stake in Labquality through a leveraged buyout by its buyout fund, Mérieux Participations 4. Existing shareholders of Labquality, including Cor Group and the management, will reinvest a portion of their proceeds into the company in connection with the transaction. Headquartered in Helsinki, Finland, Labquality is a Nordic player specialized in EQA, CRO activities and regulatory affairs, with a strong local presence in Central and Eastern Europe. The company provides a comprehensive array of services for the healthcare, medical technology, and pharmaceutical industries. The company, employing over 120 professionals and supported by a network of more than 150 external experts and consultants across its offices in Finland, Germany, and Poland, serves a diverse clientele of over 8,000 customers, including major pharmaceutical companies in over 60 countries. Mérieux Equity Partners (MxEP) is an AMF-accredited management company dedicated to equity investments in the Healthcare and Nutrition sectors. MxEP actively supports entrepreneurs and companies with differentiated products and services, giving them privileged access to its sector expertise and international network. The transaction will enable Labquality to pursue its buy & build strategy in Europe to accelerate its CRO activities while continuing strong and recurring growth in the EQA segment. Labquality will benefit from MxEP’s sector expertise and financial resources to achieve its ambition of becoming a leading European CRO and EQA platform, with fully integrated regulatory consulting capabilities to serve major customers across Europe.
Case published 4.12.2023