In recent years the global loan market has seen a shift from traditional bank lending towards private credit. Private credit has also gained increasing popularity in Finland, where corporate finance has traditionally been based on relationship banking.
16.9.2024
Private credit – an alternative to bank financing

Tero Tuomisto & Minna Korhonen
Related services
What is private credit, and why has it become so popular?
Also known as direct lending, private credit is financing provided directly to a company by a non-bank lender such as a private credit fund.
Economic uncertainty and increased regulatory requirements have led banks to become more risk-averse and traditional bank financing has become more difficult for some companies to obtain. This has resulted in an increased demand for alternative sources of financing, allowing providers of private credit to gain market share from banks.
How does private credit differ from a bank loan?
Private credit is usually provided directly to the borrower by a single lender, although we have recently seen private credit provided by small clubs of lenders as well. Private credit loans are in many ways like traditional bank loans in terms of maturity, pricing and documentation.
Similarly to bank loans, more and more private credit loans incorporate features like sustainability-linked pricing. The investor demand for more sustainable and greener financing can also be seen in the private credit market. This will direct the flow of funds in the future more often to companies which support the green transition.
What sets private credit apart is the flexibility that it can offer to the borrower. As private credit providers are not bound by stringent capital and other regulatory requirements, they can often provide borrowers with more flexible terms than banks can, such as higher leverage and a larger portion of bullet repayments or balloon repayments. This allows companies to take advantage of investment and growth opportunities which may not otherwise be possible. Because of this flexibility, private credit has been an attractive option for example for borrowers with lower credit ratings, which may not be able to secure traditional bank financing on commercially viable terms and are unable to issue bonds.
Pros and cons of private credit
As with any type of financing, private credit has its own advantages and disadvantages that borrowers should consider when evaluating their funding options.
Pros
- Flexibility: Private credit often means more flexible terms for the borrower and a somewhat smoother negotiation process. As the borrower generally deals with a single lender, getting consent and modifying financing terms tend to be simpler.
- Access to expertise: Unlike banks, private credit providers often have the capacity to support the borrower’s business by providing access to their own business expertise. This can be particularly beneficial for a borrower seeking growth in a challenging economy.
- Confidentiality: The limited number of parties involved in each private credit deal ensures that the terms remain confidential.
Cons
- Higher cost, more restrictions: Private credit tends to be more expensive and comes with stricter lender protections than bank loans due to the typically higher risk profile of borrowers who opt for private credit.
- Lack of banking relationship: In certain cases, the lack of a banking relationship may be an issue as private credit funds are not able to provide access to other banking services that companies need. Moreover, while there is no record of this happening in reality, it has been suggested that a private credit fund might adopt a harsher stance on enforcement if the borrower defaults on the loan.
- Lack of visibility: Although confidentiality is a great bonus for both the borrower and the lender, the lack of access to data makes it more difficult for market participants to track deal volumes and market trends.
The future of private credit
While bank lending is expected to become more attractive to borrowers as interest rates fall, it is still likely that there will be a demand for private credit. It is even believed that the market share of private credit in corporate lending will continue to grow.
The benefits of private credit remain attractive to borrowers, and the availability of private credit is expected to increase as investors continue to invest in private credit funds in pursuit of strong returns. An increase in supply is likely to result in tougher competition between private credit providers, which may lead to lower pricing and terms more favourable to borrowers overall.
Latest insights
Article published 21.5.2025 – Banking & Finance
Sustainable finance reimagined: What you need to know about the 2025 updates to green, social, and sustainability-linked loan principles
 Article published 20.1.2025 – Banking & Finance
The LMA’s new model provisions for green loans and green loan terms promote sustainable finance
Article published 2.10.2024 – Banking & Finance
Sustainable finance is vital for achieving the objectives of the green transition
Article published 14.5.2024 – Banking & Finance
The Green Bond label brings predictability, but issuers may have doubts due to the stringent rules

Minna Korhonen & Anna-Sofia Alahuita
Minna Korhonen & Anna-Sofia Alahuita
Minna Korhonen
Tero Tuomisto & Valter Olkkonen
Latest references
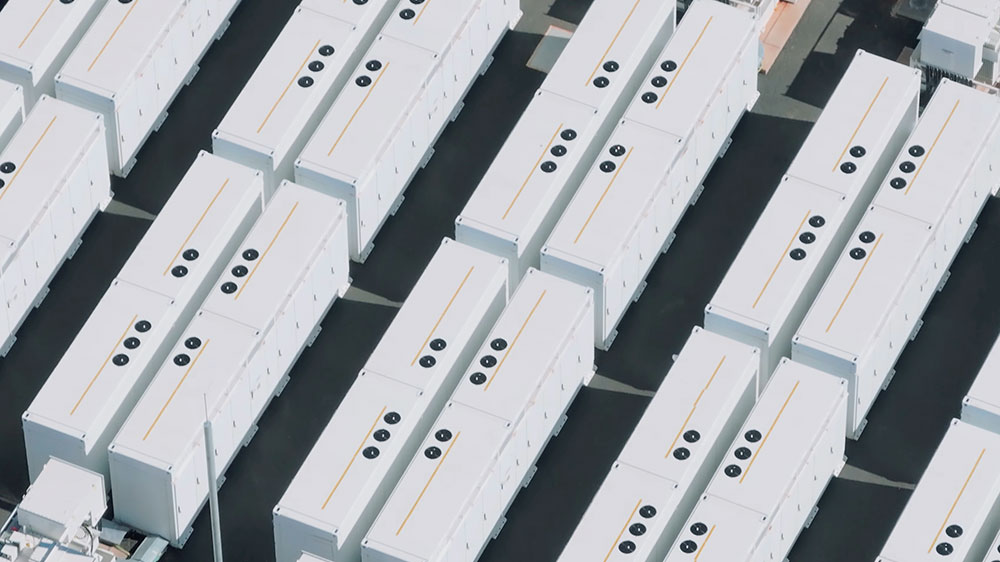
Nala Renewables – Development, acquisition and financing of battery energy storage system (BESS) project
We advised Nala Renewables on the Finnish law aspects of the development, acquisition and financing of its battery energy storage system (BESS) project in Vuolijoki, Finland. The project comprises a 125 MW / 250 MWh battery energy storage system. Our advice extended beyond financing to the transaction’s legal due diligence and the acquisition of the project company. We also advised on key project contracts and financing documentation for the project finance facilities provided by Coöperatieve Rabobank U.A. The project is part of Nala Renewables’ growing portfolio of battery storage assets in Finland and the wider Nordic region, supporting the integration of renewable energy and contributing to the flexibility and stability of the Finnish electricity grid.
Case published 3.11.2026
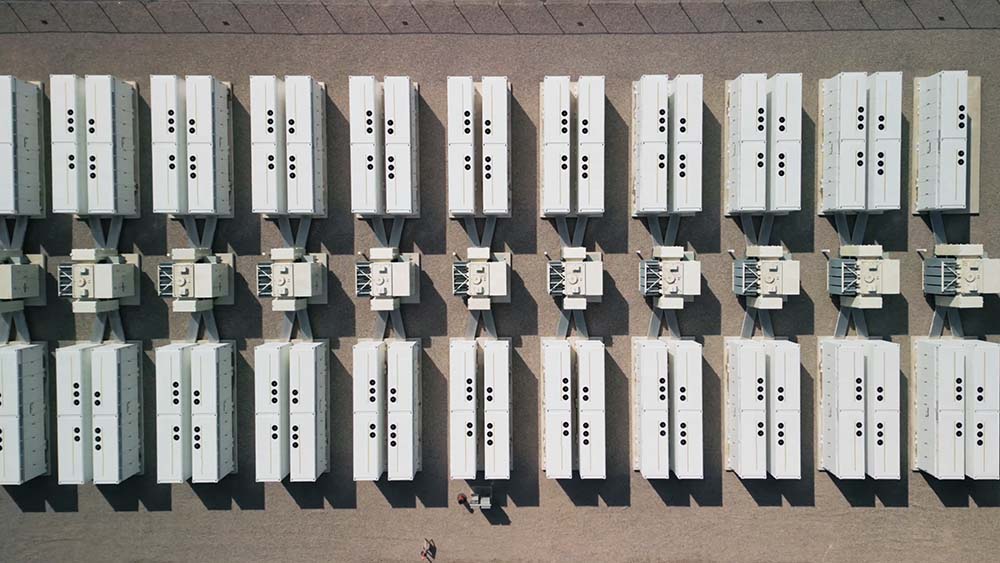
Delta Capacity – Project financing of two battery energy storage systems (BESS)
We advised Delta Capacity AG in a project financing of two battery energy storage systems (BESS). The financed projects are among the largest BESS developments in Finland to enter construction with 250 MW / 600 MWh combined capacity. The financing was provided by Société Générale with support from Finnvera. Construction of both projects, located in Lapinlahti and Teuva, has already begun and the commercial operations are targeted to commence in late 2027 with partial tolling agreements already in place for both assets. The project in Lapinlahti is executed in partnership with Covenergo, while the project in Teuva is executed in partnership with Strioga Family Foundation. Delta Capacity is a Swiss developer of utility-scale battery storage systems. The projects strengthen Delta Capacity’s growing Nordic portfolio and support the flexibility of Finland’s electricity system by adding energy storage capacity, enabling production optimization as well as participation in electricity markets and reserve services.
Case published 28.10.2026
NoHo Partners – EUR 50 million secured notes and EUR 97 million senior secured facilities agreement
We advised NoHo Partners Plc on the issuance of EUR 50 million senior secured floating rate notes. The notes have a tenor of four years and mature on 10 September 2030. The notes bear interest at a rate of three-month EURIBOR plus a margin of 4.375 per cent. per annum. The notes were allocated to a mix of domestic and international investors. We also advised NoHo Partners on the negotiation of its new senior facilities agreement. The facilities agreement comprises a EUR 60,000,000 term loan facility, a EUR 10,000,000 capex facility and a EUR 27,000,000 revolving credit facility. “We are delighted by the interest investors have shown in the company’s Notes, which reflects confidence in our strategy. The successful issuance of the Notes, together with the new loan agreement, extends the maturity profile of our financing and enables the company to continue executing its growth strategy going forward. I would like to thank all investors for their participation, as well as our partner bank for the excellent execution of the Notes issuance”, says Jarno Suominen, CEO of NoHo Partners. OP Corporate Bank plc acted as the sole lead manager and bookrunner for the issue of the notes. NoHo Partners Plc is a Finnish group established in 1996, and it specialises in restaurant services being the creative innovator of the Northern European restaurant market. The company was listed in Nasdaq Helsinki in 2013 becoming the first Finnish listed restaurant company, and it has continued to grow strongly throughout its history. NoHo Partners’ vision is to be the leading restaurant operator in Northern Europe.
Case published 4.9.2026
Aspo – Demerger and finance matters
We advised Aspo Plc, ESL Shipping Ltd and AtoBatC Shipping AB in relation to finance matters in connection with the demerger of Aspo, by which all the shares in ESL Shipping Ltd held by Aspo, together with the related assets and liabilities, will be transferred to a new independent company to be named ESL Shipping Group Plc. Aspo intends to apply for the shares of ESL Shipping Group to be admitted to trading on the regulated market of Nasdaq Helsinki. It is further intended that Aspo be renamed Telko Group Plc.
Case published 19.8.2026