In Finland, employees are entitled to certain tax deductions due to remote working and the COVID-19 pandemic for the 2020 tax year. You can claim a deduction, for example, for a home office, purchased tools or, under certain conditions, for travel expenses between your holiday home and your workplace. This is worth keeping in mind when you get your pre-completed tax return in the MyTax service this spring.
7.4.2021
What Tax Deductions Can You Make Due to the Pandemic?
Mikko Alakare
Tags
Many expenses relating to remote work can be deducted in taxation, which means that they reduce the amount of your taxable income as an employee. You can apply for deductions by supplementing your tax proposal. This is easiest to do in the MyTax online service. It is worth claiming deductions you are entitled to, because this directly increases the amount of your net pay.
Automatic EUR 750 Deduction for the Production of Income
All employees receive an automatic EUR 750 deduction for the production of income. If your expenses for the production of income are less than EUR 750, you do not have to report them.
Workspace Deduction
You have two options for claiming a deduction for remote working expenses: either a standard deduction based on a formula or a deduction based on actual costs.
You can claim the formula-based workspace deduction even if you don’t have a separate home office. The formula covers the rent for the workspace, electricity, heating, cleaning and furnishings. You do not have to provide grounds for your claim. The deduction is employee-specific, so if your spouse also remote works in your shared home, you can both claim the formula-based deduction.
The formula-based workspace deduction depends on the number of days you have worked remotely. The workspace deduction in 2020 is:
You can also choose to deduct the actual expenses related to your workspace. If you choose this option, you must be able to present the receipts for your purchases to the Finnish Tax Administration.
It is only worth claiming the deduction based on actual costs if the costs of your workspace exceed the amount of the formula-based deduction. If spouses who both remote work in their shared home claim actual expenses, the deductible sums are distributed between the spouses based on an account presented by them.
Work Tools Are Deductible
In addition to the workspace deduction, you can deduct the costs of work tools you have purchased, such as computer monitors and keyboards. If the tools purchased are mainly used for work, you can deduct the full purchase price. If the tools are partially used for work and partially used for other things, you can deduct 50% of the purchase price.
If your employer lends you tools, i.e. your employer still owns them, they do not count as a taxable benefit. However, if your employer buys tools for you that you own, the market value of the tools will be counted as taxable wages.
Data Connection
You can also deduct the costs of a data connection you have acquired yourself. You can deduct 100% of the costs if the data connection is fully used for work. If the connection is partly used for work, you can deduct 50%. If spouses share the data connection for the production of income, they halve the above percentages.
If your employer provides you with a data connection for work purposes, you do not have to pay tax on it regardless of whether the connection is in work use or private use.
Travel and Face Mask Expenses
You can claim the expenses for commuting to work only for the days when you went to the workplace. The personal liability threshold for commuting expenses is EUR 750, and you should only claim your travel expenses if they are higher than this sum. Claim the costs according to the least expensive means of transportation.
If you have been working from a holiday home, the deductible expenses for travel between your holiday home and workplace can never be greater than the commuting expenses between your permanent home and your workplace. If your holiday home is further away from your workplace than your permanent home, you can deduct the expenses based on the cheapest method of transportation between your permanent home and your workplace. If your holiday home is closer to your workplace than your permanent home, you can deduct the expenses based on the cheapest method of transportation between your holiday home and your workplace.
The cost of face masks worn on public transport are deductible if you buy the masks yourself. Deduct the costs of face masks as part of your commuting expenses. The deduction is two euros per day for each day you have travelled between your home and work after 13 August 2020, when the Finnish Institute for Health and Welfare issued a face mask recommendation.

Latest news
Latest references
Efima – Sale of AI business
We advised Efima Oyj on the sale of its AI business to Better Care Technologies Oy. The transaction included Efima’s Moiva AI platform developed for the care sector, the related technology and brand, customer contracts, and the experts working in the business. Efima is a Finnish digital company that supports the sustainable growth of large and mid-sized companies by streamlining their business processes and by creating competitive advantage through the innovative use of artificial intelligence and data. The company has nearly 200 experts based in Helsinki and Tampere.
Case published 21.9.2026
Neoen – Sale of data centre
We advised Neoen Renewables Finland Oy, part of the French Neoen Group, in its sale of a data centre project to a consortium consisting of international data centre developers and operators. This marked Neoen’s first data centre development project in Finland. Founded in 2008, Neoen is one of the world’s leading independent renewable energy producers. The company operates in 15 countries. It develops, finances, builds, owns, and operates solar power plants, wind farms, and battery storage systems. Neoen Group is owned by global alternative asset manager Brookfield Corporation.
Case published 17.9.2026
Jolt Capital and Tesi – Investment in VEV
We advised Jolt Capital and Tesi in connection with their investment in VEV, a leading provider of commercial fleet electrification solutions. The investment, led by Jolt Capital with Tesi as co-investor, will support VEV’s next phase of growth and expansion across Europe. As part of the transaction, VEV became an independent company following the acquisition of Vitol’s stake in the business. Founded by Vitol, VEV provides integrated fleet electrification solutions combining fleet strategy, charging infrastructure, energy supply and operational services. Through its VEV IQ platform, the company supports more than 6,000 commercial electric vehicles across Europe and has been deployed across more than 600 sites spanning the transport, logistics and waste sectors. Jolt Capital is a private equity firm focused on growth investments in European deeptech companies. Tesi is a Finnish state-owned investment company that promotes Finnish business and economic growth through investments. We advised Jolt Capital and Tesi on the equity financing and structuring aspects of the transaction. International law firm Goodwin advised the investors on the acquisition of VEV.
Case published 10.9.2026
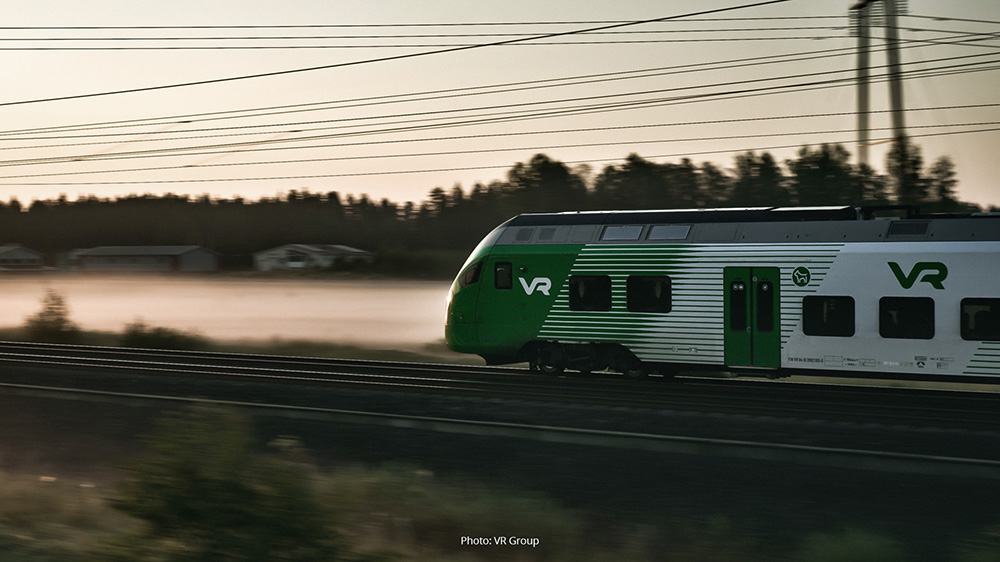
VR Group – Intellectual property matters
VR-Group Plc is a transport and logistics group owned by the Finnish State, operating passenger and freight rail transport in Finland with activities also in the Swedish market. VR Group provides passenger, logistics and maintenance services with over 160 years’ experience in developing responsible transport of the future. We advise VR Group in intellectual property matters as part of the company’s wider brand protection efforts. Our assignments have included advice on copyright, design rights and trademarks, focusing on the protection of the company’s visual identity – including its distinctive green colour – in connection with transport services as part of a comprehensive IP protection strategy. VR Group’s consistent brand building has also received recognition, including the Finland Chamber of Commerce’s Brand of the Year award in 2026. In the competition, brands were viewed comprehensively from various perspectives, including their story, strategic role, brand renewal ability and intellectual property protection. The jury found that VR had understood the importance of the protection of its brand as part of a comprehensive business strategy.
Case published 9.9.2026