On 19 May 2016, the Supreme Administrative Court of Finland (the SAC) issued two decisions concerning the right to deduct interest costs within a group of companies. The SAC ruled that the Finnish branch of an international group of companies was not able to deduct interest costs paid by the branch to a foreign group entity in its taxation.
20.5.2016
Two Important Finnish Court Decisions: Interest Deductions on Intra-group Loans
Related services
Allocation of Income and Assets to a PE
In both cases, a foreign entity belonging to a group of companies had established a branch in Finland, and shares of another operating group company had been allocated to the branch after an intra-group share acquisition. Further, the intra-group loans related to the share acquisitions had been allocated to the branch.
The specific question in these cases was whether the shares transferred to the branch could be treated as assets of the branch and whether the interest costs related to the share acquisitions would have been deductible from the taxable income of the branch. In both cases, the SAC ruled that the companies had not been able to provide sufficient business reasons for the argument that the shares could belong to the business carried out by the branch. Therefore, the branch was not able to deduct the interest costs related to the share acquisition in its taxation.
Although the outcome of the rulings on the main question was the same, it is worth paying attention to the different reasoning used in these cases. In decision 2016:71, the branch had only limited business functions and personnel. The SAC held that the representatives of the branch did not exercise control in the underlying operating company, and such control was actually held by the foreign entity of the branch or the parent company of the whole group. Thus, the shares in the operating company were not in the permanent use of the business of the branch and were not held as assets belonging to the branch.
Application of the General Anti-avoidance Rule
In its decision 2016:72, the SAC ruled by vote that the transfer of shares of the operating company under the Finnish branch was actually a part of a series of arrangements, and these arrangements should be evaluated as a whole while also taking into account the Finnish anti-avoidance rule. In this case, the shares of the operating company were first transferred from an US company to a Swedish company, after which the shares were allocated to the Finnish branch. Based on this evaluation, the SAC held that the intention of the arrangements was considered to be to avoid the payment of tax by taking advantage of the interest deductions and group contribution regime. Therefore, the SAC ruled that, as a result of the arrangements, the interest costs were not deductible.
Implications on Tax Planning
The rulings are significant, as they challenge the position of branches as holding vehicles used in share acquisitions between intra group companies. Under the circumstances presented in these cases, the court stated, among other things, that taking into account the OECD model income tax convention commentary, the shares and the loan could not be allocated to the branch. Further, the court has underlined the significance of the business reasons behind tax planning and in evaluating the applicability of the general anti-avoidance rule. There are currently similar cases pending in the Finnish courts and these rulings are likely to have effect on their outcome depending on the relevant circumstances.
The Finnish Tax Administration has issued an announcement according to which it will provide guidance on the implications of the rulings on Tax Administration’s guidelines and interpretations.
Latest news
Latest references
Efima – Sale of AI business
We advised Efima Oyj on the sale of its AI business to Better Care Technologies Oy. The transaction included Efima’s Moiva AI platform developed for the care sector, the related technology and brand, customer contracts, and the experts working in the business. Efima is a Finnish digital company that supports the sustainable growth of large and mid-sized companies by streamlining their business processes and by creating competitive advantage through the innovative use of artificial intelligence and data. The company has nearly 200 experts based in Helsinki and Tampere.
Case published 21.9.2026
Neoen – Sale of data centre
We advised Neoen Renewables Finland Oy, part of the French Neoen Group, in its sale of a data centre project to a consortium consisting of international data centre developers and operators. This marked Neoen’s first data centre development project in Finland. Founded in 2008, Neoen is one of the world’s leading independent renewable energy producers. The company operates in 15 countries. It develops, finances, builds, owns, and operates solar power plants, wind farms, and battery storage systems. Neoen Group is owned by global alternative asset manager Brookfield Corporation.
Case published 17.9.2026
Jolt Capital and Tesi – Investment in VEV
We advised Jolt Capital and Tesi in connection with their investment in VEV, a leading provider of commercial fleet electrification solutions. The investment, led by Jolt Capital with Tesi as co-investor, will support VEV’s next phase of growth and expansion across Europe. As part of the transaction, VEV became an independent company following the acquisition of Vitol’s stake in the business. Founded by Vitol, VEV provides integrated fleet electrification solutions combining fleet strategy, charging infrastructure, energy supply and operational services. Through its VEV IQ platform, the company supports more than 6,000 commercial electric vehicles across Europe and has been deployed across more than 600 sites spanning the transport, logistics and waste sectors. Jolt Capital is a private equity firm focused on growth investments in European deeptech companies. Tesi is a Finnish state-owned investment company that promotes Finnish business and economic growth through investments. We advised Jolt Capital and Tesi on the equity financing and structuring aspects of the transaction. International law firm Goodwin advised the investors on the acquisition of VEV.
Case published 10.9.2026
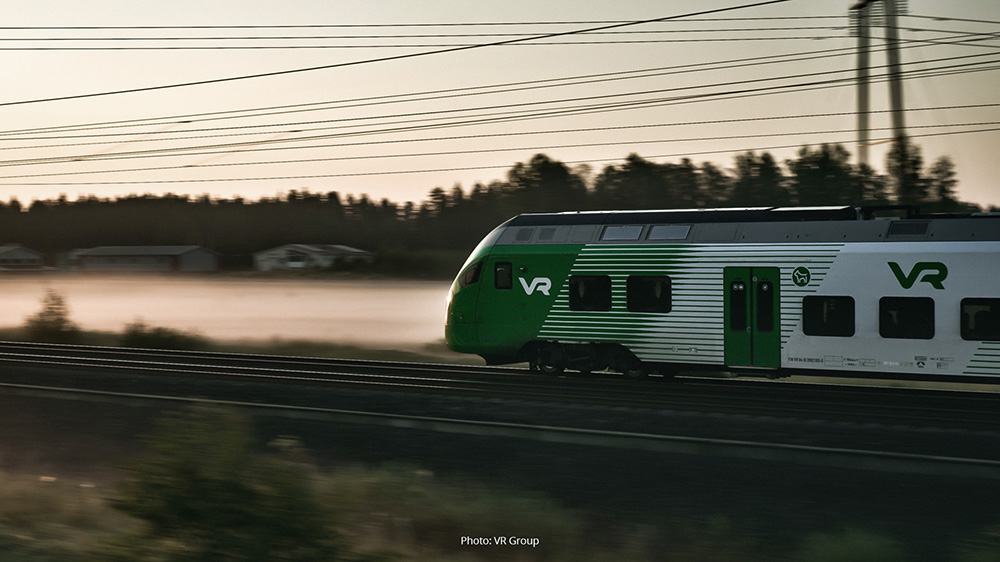
VR Group – Intellectual property matters
VR-Group Plc is a transport and logistics group owned by the Finnish State, operating passenger and freight rail transport in Finland with activities also in the Swedish market. VR Group provides passenger, logistics and maintenance services with over 160 years’ experience in developing responsible transport of the future. We advise VR Group in intellectual property matters as part of the company’s wider brand protection efforts. Our assignments have included advice on copyright, design rights and trademarks, focusing on the protection of the company’s visual identity – including its distinctive green colour – in connection with transport services as part of a comprehensive IP protection strategy. VR Group’s consistent brand building has also received recognition, including the Finland Chamber of Commerce’s Brand of the Year award in 2026. In the competition, brands were viewed comprehensively from various perspectives, including their story, strategic role, brand renewal ability and intellectual property protection. The jury found that VR had understood the importance of the protection of its brand as part of a comprehensive business strategy.
Case published 9.9.2026