On 2 December 2022, a draft proposal for a temporary tax on the profits of firms in the electricity and fossil fuels sector was sent out for consultation by the Ministry of Finance. Pursuant to the proposal, the tax would be paid by certain companies in the electricity sector operating in the Finnish market and certain companies in the fossil fuels sector. The taxable profits would be subject to a 33% tax rate. The proposed tax would be collected in addition to the usual corporate income tax (20%), and it would be paid to the state. The profit tax would not be tax deductible for the company.
19.12.2022
Finland proposes a new windfall tax act
Kanerva Sunila, Mikko Alakare, Noora Ahonen & Samuli Tarkiainen
Companies subject to tax
The windfall tax would apply to those companies in the electricity sector that are active in the generation or supply of electricity. In addition to electricity producers, wholesalers and retailers would thus be liable to this tax as well. It is worth noting that in this respect, the proposal would deviate from the European Union Regulation (EU) 2022/1854 on which it is based and which requires the application of a cap on revenues to electricity producers. However, the proposed tax would only apply to operators whose generation and supply operations exceed the limits for operations of minor significance laid down in the Decree of the Ministry of Economic Affairs and Employment on the unbundling of electricity business (1305/2019). In case of group companies, tax liability would be determined for each company separately. In other words, the assessment of whether the limit for operations of minor significance is exceeded would be done on a company-specific basis.
Among the companies in the fossil fuel sector, windfall tax would be applied to those with over 75% of their turnover coming from crude oil or natural gas production, refined products of crude oil or coal products.
Determination of taxable profit
For companies in the electricity sector within the scope of application of the proposed tax, the tax would be calculated based on the results of electricity operations other than electricity system operations (‘electricity operations’). Any profit generated by a permanent establishment abroad would not be taken into account when calculating the results of the electricity operations. The results of the electricity operations would refer to the difference between the taxable income of the electricity business and the deductible expenses and other deductible amounts recognised in the tax year. With a few exceptions, the taxability of income and the deductibility of expenses, as well as the recognition of income and expenses, would be determined in accordance with the Act on the Taxation of Business Income. However, the part of the electricity operations’ profit that corresponds to a 5% annual profit calculated on the equity stated in the balance sheet of the electricity business would not be subject to tax. The aim of the exclusion of a 5% return on capital is to avoid an adverse impact on the investments in electricity production. The novelty lies in using the results of the ‘electricity operations’ to determine the profit subject to tax, and the interpretation issues that will potentially arise from this will likely need to be resolved in case law.
As for the companies in the fossil fuel sector within the scope of application of the proposed tax, they would pay tax on the part of their result of operations exceeding a 5% annual profit calculated on the equity stated in the balance sheet. The assets and liabilities of a permanent establishment would not be taken into account when calculating this five percent annual profit. As the companies in the fossil fuel sector have no similar unbundling obligations as the electricity sector companies, the profit would be calculated based on the company’s entire result of operations, i.e. the difference between the income and expenses during the tax year.
What next?
The consultation period ended on 12 December 2022. The new windfall tax act and the related amendments on the Act on the Taxation of Business Income are intended to enter into force as soon as possible. In accordance with the proposal, the tax would apply to any profits concerning tax year 2023. In practice, the tax would be collected afterwards during 2024. Due to the urgency of the proposal, it is likely that the legislative drafting will proceed swiftly once the consultation has ended. Pursuant to Regulation (EU) 2022/1854, Member States shall adopt and publish measures implementing the solidarity contribution by 31 December 2022. The provisions of said Regulation regarding the cap on electricity producers’ revenues became applicable on 1 December 2022. The proposal is expected to be submitted to the Parliament in the last week of the year.
Latest news
Latest references
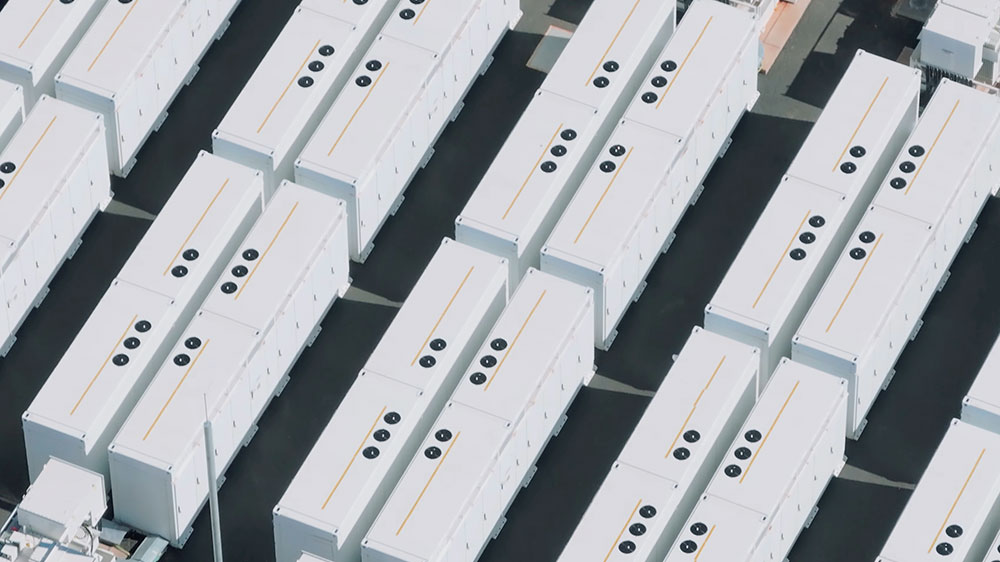
Nala Renewables – Development, acquisition and financing of battery energy storage system (BESS) project
We advised Nala Renewables on the Finnish law aspects of the development, acquisition and financing of its battery energy storage system (BESS) project in Vuolijoki, Finland. The project comprises a 125 MW / 250 MWh battery energy storage system. Our advice extended beyond financing to the transaction’s legal due diligence and the acquisition of the project company. We also advised on key project contracts and financing documentation for the project finance facilities provided by Coöperatieve Rabobank U.A. The project is part of Nala Renewables’ growing portfolio of battery storage assets in Finland and the wider Nordic region, supporting the integration of renewable energy and contributing to the flexibility and stability of the Finnish electricity grid.
Case published 3.11.2026
Foundation Clinic – Funding Round
We advised Foundation Clinic in connection with its funding round backed by a group of prominent Finnish technology entrepreneurs and investors, including founders behind Supercell and Wolt. Foundation Clinic is a Finnish healthcare company developing a new approach to private healthcare focused on preventive, data-driven and continuous care. The company aims to combine comprehensive health data with ongoing medical care to identify and address health risks at an early stage.
Case published 29.10.2026
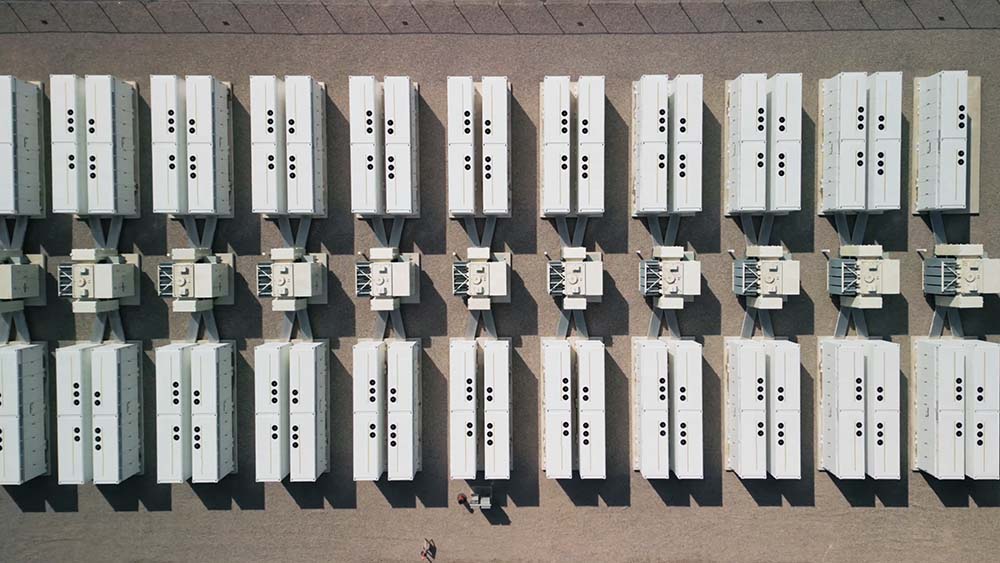
Delta Capacity – Project financing of two battery energy storage systems (BESS)
We advised Delta Capacity AG in a project financing of two battery energy storage systems (BESS). The financed projects are among the largest BESS developments in Finland to enter construction with 250 MW / 600 MWh combined capacity. The financing was provided by Société Générale with support from Finnvera. Construction of both projects, located in Lapinlahti and Teuva, has already begun and the commercial operations are targeted to commence in late 2027 with partial tolling agreements already in place for both assets. The project in Lapinlahti is executed in partnership with Covenergo, while the project in Teuva is executed in partnership with Strioga Family Foundation. Delta Capacity is a Swiss developer of utility-scale battery storage systems. The projects strengthen Delta Capacity’s growing Nordic portfolio and support the flexibility of Finland’s electricity system by adding energy storage capacity, enabling production optimization as well as participation in electricity markets and reserve services.
Case published 28.10.2026
Martela Corporation – Directed share issue and combination of share series
We acted as legal adviser to Martela Corporation in its directed share issue, through which Martela raised gross proceeds of approximately EUR 7.2 million to strengthen the company’s financial position and liquidity and to create headroom for continuing the necessary development and efficiency measures. In connection with the directed share issue, Martela’s unlisted series K shares, which carried greater voting rights, were combined with its listed series A shares. Following the combination, the company has only one share series, which is traded on the regulated market maintained by Nasdaq Helsinki Ltd, with each share carrying one vote and otherwise identical rights. Martela is a Nordic leader specialising in user-centric working and learning environments. With over 80 years of experience, Martela creates the best places to work and offers its customers the Martela Lifecycle solutions which combine furniture and related services into a seamless whole.
Case published 27.10.2026