The latest version of the WTS Global Financial Services Infoletter presents tax developments from ten countries with a focus on the international Financial Services industry. The newsletter covers a diverse range of taxation-related topics affecting the Financial Services industry, for instance, the Indonesian taxation of crypto assets, foreign loans to Chinese high-tech firms, EU WHT refunds to third-country funds as well as several recent and important court decisions.
6.10.2022
C&S Authors the Finland Chapter of WTS Global Financial Services Infoletter
Anette Sainio
Related services
Tags
Our tax experts Sari Laaksonen and Anette Laitinen authored the Finland Chapter. The other countries covered are:
Read the WTS Global Newsletter.
This article was first published in WTS Global Newsletter.
Exit tax proposed for individuals – proposal includes several problematic elements and would mean a major change in Finnish capital gains taxation
On 12 August 2022, the Ministry of Finance published a preliminary draft government proposal concerning a so-called exit tax on private individuals. The exit tax would significantly broaden Finland’s taxing rights and change Finland’s capital gains taxation. The law is to come into force and be applied as early as 2023.
The proposed exit tax in short
According to the proposal, the exit tax would affect individuals with significant assets who transfer their tax domicile from Finland to abroad. The tax base would represent the increase in value of movable assets that occurred while residing in Finland and the tax would be levied in accordance with the Finnish capital gains taxation. The capital gains tax rates in Finland currently vary between 30–34 per cent. The exit tax would be levied even in cases where the increase in value is realised only after the person already resides abroad.
Most movable assets would be included in the tax base for the new exit taxation – for example, company shares, shares in investment funds, options, futures, pension insurances and virtual currencies. The tax would not, however, apply to real estate assets, to which Finland already has broad taxing rights.
Furthermore, the new exit taxation only takes place when the individual moving from Finland has had their tax residency in Finland for at least 4 years within the last 10 years before moving away. This includes foreign citizens who have resided in Finland for the stated period.
Also, the value of taxable assets must be at least EUR 500,000 and the imputed capital gain must be at least EUR 100,000 on the date the individual moves from Finland. In practice, these thresholds mean that the tax would only affect wealthy private individuals, thus raising the question of whether such a narrowly defined tax would violate taxpayer equality and tax fairness.
The income subject to the exit tax would be considered income in the tax year in which the individual moves from Finland. However, the individual would have the right to postpone the payment of the tax until the assets in question are disposed of by way of sale or gift. This exemption would require that the individual files an annual notification to the Finnish Tax Administration reporting that the assets they owned when moving from Finland are still in their possession. Exit tax would no longer be applicable if the assets are not disposed of within eight tax years after the year of moving out of Finland.
The exit tax has caused a lot of public debate – the proposal bears the risk of adverse side effects and may not generate any significant tax revenue for the state
The proposed exit tax has already sparked widespread public debate and further discussion is expected as the legislative process continues in the government this fall. While the purpose of the exit tax is to prevent tax evasion, it is very likely that instead of solving problems of tax evasion, the tax would lead to undesirable side effects.
From the perspective of taxpayers, the proposed exit taxation is particularly problematic, as it could lead to the double taxation of private individuals in several ways. As mentioned above, another problematic aspect of the proposal is that the exit tax would apply only to a small, wealthy segment of individuals. Moreover, the proposed tax may have a negative impact on Finland’s competitiveness in international markets. It could potentially make Finland a less attractive place to work and make it more difficult to attract foreign talent to Finnish companies.
According to the government draft proposal, the expected annual revenue for the Finnish state from the new tax would amount to approximately 0-70 million euros. At the same time, however, the tax would impose a significant additional administrative burden on the Finnish tax authorities. Given the low expected tax revenues and the potential adverse effects the tax may induce, it is particularly questionable whether it can be justified from a Finnish tax law perspective.
Latest news
Latest references
Efima – Sale of AI business
We advised Efima Oyj on the sale of its AI business to Better Care Technologies Oy. The transaction included Efima’s Moiva AI platform developed for the care sector, the related technology and brand, customer contracts, and the experts working in the business. Efima is a Finnish digital company that supports the sustainable growth of large and mid-sized companies by streamlining their business processes and by creating competitive advantage through the innovative use of artificial intelligence and data. The company has nearly 200 experts based in Helsinki and Tampere.
Case published 21.9.2026
Neoen – Sale of data centre
We advised Neoen Renewables Finland Oy, part of the French Neoen Group, in its sale of a data centre project to a consortium consisting of international data centre developers and operators. This marked Neoen’s first data centre development project in Finland. Founded in 2008, Neoen is one of the world’s leading independent renewable energy producers. The company operates in 15 countries. It develops, finances, builds, owns, and operates solar power plants, wind farms, and battery storage systems. Neoen Group is owned by global alternative asset manager Brookfield Corporation.
Case published 17.9.2026
Jolt Capital and Tesi – Investment in VEV
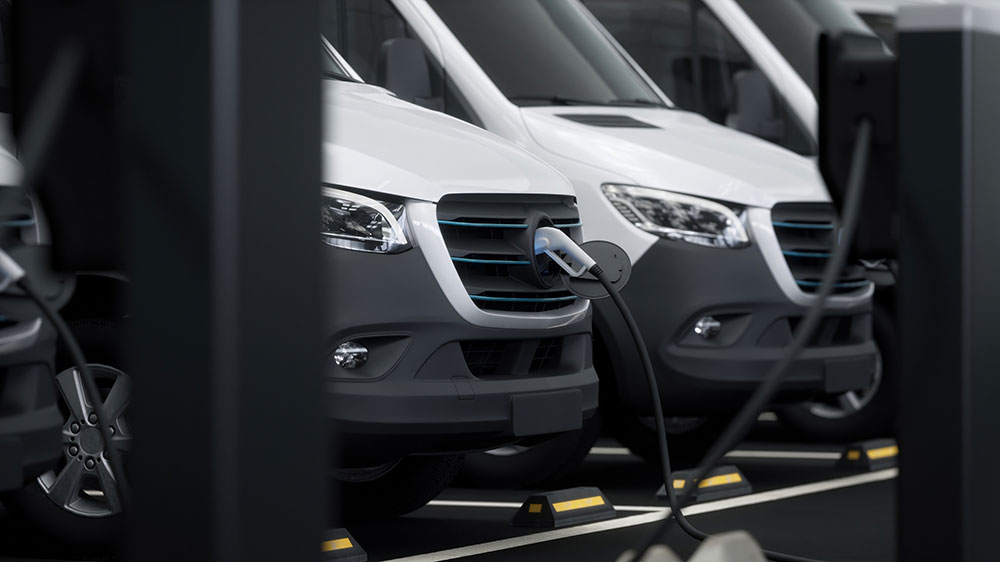
We advised Jolt Capital and Tesi in connection with their investment in VEV, a leading provider of commercial fleet electrification solutions. The investment, led by Jolt Capital with Tesi as co-investor, will support VEV’s next phase of growth and expansion across Europe. As part of the transaction, VEV became an independent company following the acquisition of Vitol’s stake in the business. Founded by Vitol, VEV provides integrated fleet electrification solutions combining fleet strategy, charging infrastructure, energy supply and operational services. Through its VEV IQ platform, the company supports more than 6,000 commercial electric vehicles across Europe and has been deployed across more than 600 sites spanning the transport, logistics and waste sectors. Jolt Capital is a private equity firm focused on growth investments in European deeptech companies. Tesi is a Finnish state-owned investment company that promotes Finnish business and economic growth through investments. We advised Jolt Capital and Tesi on the equity financing and structuring aspects of the transaction. International law firm Goodwin advised the investors on the acquisition of VEV.
Case published 10.9.2026
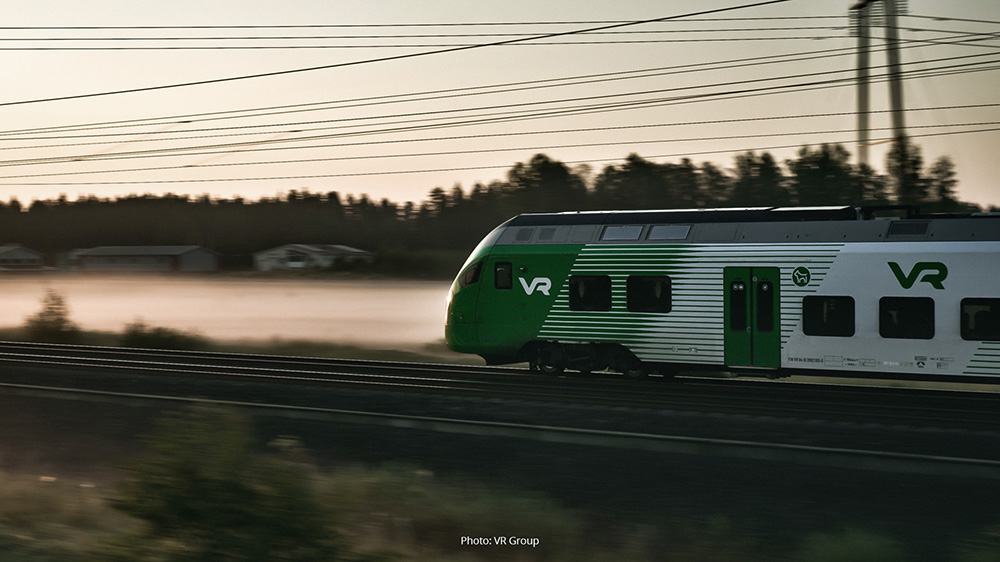
VR Group – Intellectual property matters
VR-Group Plc is a transport and logistics group owned by the Finnish State, operating passenger and freight rail transport in Finland with activities also in the Swedish market. VR Group provides passenger, logistics and maintenance services with over 160 years’ experience in developing responsible transport of the future. We advise VR Group in intellectual property matters as part of the company’s wider brand protection efforts. Our assignments have included advice on copyright, design rights and trademarks, focusing on the protection of the company’s visual identity – including its distinctive green colour – in connection with transport services as part of a comprehensive IP protection strategy. VR Group’s consistent brand building has also received recognition, including the Finland Chamber of Commerce’s Brand of the Year award in 2026. In the competition, brands were viewed comprehensively from various perspectives, including their story, strategic role, brand renewal ability and intellectual property protection. The jury found that VR had understood the importance of the protection of its brand as part of a comprehensive business strategy.
Case published 9.9.2026