Exit strategy may not be the first thing on your mind when starting your startup. However, it should be. When you start your company, one of the key issues is to make a plan for how to get your money back at some stage in the future. And that interests your investors as well. How you finish is as essential to as how you start. You need to determine either your exit or your payoff, and you want to make sure that you have that option when the time comes.
16.7.2014
Exit Strategy Checklist for Cashing in Your Startup – Legal Advisor’s Perspective
Related services
From a legal advisor’s perspective, there are several options available as an exit strategy but, nowadays, the most common way is to sell your company. Moreover, a trend of early exits seems to attract many startups, and companies are often sold only 3—5 years after they are founded. Initial public offering (IPO) used to be a popular way to exit, but today companies find it much less tempting. Going public is such a massive project, requiring a proper infrastructure and a lot of effort and money, that most of the startups do not want to deal with it. Furthermore, as startups are typically exiting in such an early stage, most of them would not even fulfil the prerequisites required for an IPO. This is why we want to concentrate on acquisition – how to sell your startup company in a legally simple and easy way.
We have made a legal checklist for ‘how to sell a startup’. This checklist is useful when selling the whole stock or parts of it, or when just e.g. licensing the technology of your startup. Moreover, it is suitable not only when exiting, but also in every financing round. Keep in mind that getting capital investors involved in financing rounds may significantly increase the chances of a hefty exit of your startup. These are the reasons why this checklist is already worth taking out from day one of starting your business.
1. Keep your documentation in order, up-to-date and always in electronic form
It is crucial to have your documents available when you need them. Usually the need comes when you least expect it, and at the time of an acquisition or a financing round missing documentation can cause extra work, time and costs, unnecessary risks and other inconveniences.
Make sure that you conclude written agreements whenever possible and keep them properly recorded and safe. The same applies to statutory corporate documents. Also mind that your intellectual property rights are all properly protected, registered and duly transferred to the company, and that you have their documentation up to date.
The key is to keep legal risks low in the company all the time. In theory, the company should always withstand a check by a professional third party. In any case, there will be a due diligence (DD) phase in the event of selling your company or acquiring equity sponsors. Due diligence is an inspection of business made by a potential acquirer/equity sponsor. If the above-mentioned issues are maintained well, the company should be ready for a DD anytime.
2. Mind the confidential information of your company
During the DD phase, you need to be ready to answer a broad range of questions concerning your company. Still, be careful about how much and what kind of confidential information you want to introduce to potential acquirers at different stages of the DD phase.
A non-disclosure agreement (NDA) is essential before giving any confidential information to a potential acquirer. Bear in mind that you may be giving this information to your competitor and that they are not yet legally bound to buy your business at that stage. In particular, information relating to the most essential functions of business should typically not be given until the very end of the DD phase and not without sufficient deal security. However, the scope of an NDA depends on the nature of your company, and practicality should be kept in mind when protecting confidential information.
3. Use letters of intent to maximise strategic advantage
A letter of intent (LOI, also known as a term sheet) is a document outlining an agreement between the parties before the final sale and purchase agreement or the investment agreement is finalised. It basically determines how the deal is structured. The most common purposes of a LOI are to clarify the key points of transaction, declare officially that the parties are currently negotiating and provide safeguards in case the deal collapses. LOI is usually not entirely binding, but it often includes a confidentiality clause (substituting an NDA) and/or covenants providing exclusive rights to negotiate.
4. Develop effective strategies when negotiating the purchase price and other terms of the deal
Negotiation skills play a significant role after (or even simultaneously with) the DD phase until reaching a consensus on the sale and purchase price and other terms of the transaction such as liabilities, non-competition restrictions etc. It is important to structure and negotiate potential earn-out elements and critical risk allocation provisions, which might mean that you will need to accept responsibility for some risks a certain time after the transaction has been made.
The Sale and Purchase Agreement (SPA) represents the mutual acceptance on an offer, as a result of commercial and pricing negotiations. At this point, before signing an SPA, analyze the terms of an acquisition agreement and ensure that the agreement corresponds to what has been agreed.
Always be prepared to exit
This is a high-level checklist for the legal issues that need to be kept in mind when selling your startup company. We would like to highlight that planning and completing the exit properly may increase the entire value of your business outstandingly. However, an acquisition as a process is like a train – to reach its destination in time and painlessly, it requires a well-designed railway track. No matter how much you love your startup and how much it has become a lifestyle for you, you need to be prepared to exit, now and always. Design your exit well ahead and make it the most profitable part of all your business processes.
Latest insights
Article published 13.5.2026 – Venture Capital & Minority Investments
Newly launched Series Seed 4.0 is a comprehensive standard seed financing documentation for the Finnish market

 Article published 28.4.2026 – Private M&A
Unlocking value in carve-outs – Why integration planning deserves top priority in every carve-out
 Article published 14.1.2026 – Tax & Structuring
VAT deductions for private equity investors under the microscope
 Article published 7.11.2025 – Capital Markets & Public M&A
AIFMD II – implications for alternative investment fund managers in Finland

Jarno Tanhuanpää, Tuomas Honkinen & Jussi Mäkikangas
Benjamin Bade, Maiju Mäkinen & Samuli Salminen
Mikko Alakare & Lotta Manu
Hannu Huotilainen & Freja Harima
Latest references
Jolt Capital and Tesi – Investment in VEV
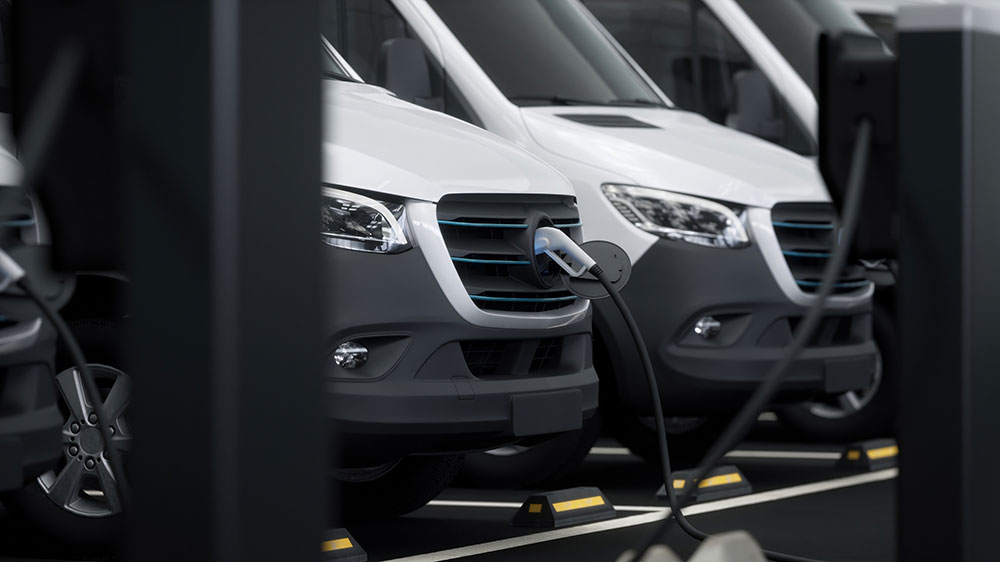
We advised Jolt Capital and Tesi in connection with their investment in VEV, a leading provider of commercial fleet electrification solutions. The investment, led by Jolt Capital with Tesi as co-investor, will support VEV’s next phase of growth and expansion across Europe. As part of the transaction, VEV became an independent company following the acquisition of Vitol’s stake in the business. Founded by Vitol, VEV provides integrated fleet electrification solutions combining fleet strategy, charging infrastructure, energy supply and operational services. Through its VEV IQ platform, the company supports more than 6,000 commercial electric vehicles across Europe and has been deployed across more than 600 sites spanning the transport, logistics and waste sectors. Jolt Capital is a private equity firm focused on growth investments in European deeptech companies. Tesi is a Finnish state-owned investment company that promotes Finnish business and economic growth through investments. We advised Jolt Capital and Tesi on the equity financing and structuring aspects of the transaction. International law firm Goodwin advised the investors on the acquisition of VEV.
Case published 10.9.2026
Topfoods – Acquisition of Delice Plus
We advised Topfoods Oy, a Triton-backed Geia Group company, on its acquisition of Oy Delice Plus Ab, a Finnish supplier of cakes and pastries. Through the acquisition, Topfoods strengthens its retail business and further reinforces its position in the cakes and pastries segment. Founded in 2008, Topfoods supplies selected food products to professional kitchens, the retail sector, and the food industry.
Case published 4.9.2026
Korona Invest – Sale of Innoflame
We advise Korona Invest and the other shareholders of Innoflame Oy on the sale of Innoflame to Sponsor Capital. The transaction makes Sponsor Capital the new majority owner of Innoflame. Korona Invest has been a shareholder of Innoflame since 2021 and, together with the other selling shareholders, has over the past five years supported the company’s growth, development and several strategically significant corporate transactions, through which Innoflame has strengthened its position as Finland’s leading product media company. The ownership change is intended to support Innoflame’s next phase of growth, including its ambition to build a significant European product media company with the capability to expand rapidly into new markets. The transaction is conditional to the customary closing conditions such as authority approvals. Innoflame is one of Finland’s leading product media specialists, helping its clients build a unified brand experience by offering the design, sourcing and management of product media as a single integrated service. Korona Invest is a Finnish private equity firm founded in 2006, specialising in buyout and growth investments in domestic small and medium-sized enterprises. It makes both majority and minority investments, structuring each project to suit the company’s growth strategy.
Case published 27.8.2026

Ugly Duckling Ventures – EUR 6.5 million funding round of Skyfora
We advised lead investor Ugly Duckling Ventures on the EUR 6.5 million funding round of Skyfora. The round also included Eviny Ventures, LUMO Labs and EIC Fund, alongside non-dilutive funding from Business Finland. The investment will support the commercial scale-up of Skyfora’s weather intelligence solutions, the expansion of partnerships with telecom operators, forecasting providers and meteorological institutions, and the continued growth of the team. Skyfora is a Finnish company developing high-resolution weather data solutions using patented technology that extracts atmospheric data from GNSS receivers embedded in existing infrastructure, such as telecom networks. By unlocking previously untapped data sources, Skyfora enables the next generation of AI-driven weather forecasting and supports improved decision-making across weather-sensitive industries. Ugly Duckling Ventures is a Copenhagen-based venture capital firm focused on early-stage Nordic B2B technology companies, with an emphasis on medtech, resilience tech and business services.
Case published 10.6.2026