In recent years, the previously rare continuation funds have become more common as a way to create liquidity in close-ended funds. Continuation funds enable the realisation of an investment in such a manner that the fund manager retains control and has the possibility to benefit from a potential future increase in value of the investment target. In this post, I present some central special characteristics of continuation funds that fund managers and investors should keep in mind.
26.4.2022
Continuation Funds as a Tool for Creating Liquidity
Related services
What Are Continuation Funds?
In an average continuation fund transaction, a continuation fund purchases one or several investment targets in a fund that is managed by the same fund manager and often near the end of its term. Investors of the existing fund have the option to either sell (i.e. redeem) their investment or to transfer it to the continuation fund. Completely new investors pay their commitments to the continuation fund, which provides liquidity for those investors of the existing fund that have decided to withdraw from the investment target. The terms and conditions of the continuation funds are negotiated between the fund manager and the new investors, and they often vary according to the asset categories that are the object of the continuation fund transaction.
When used strategically correctly, a continuation fund can satisfy the interests of the different stakeholders and achieve several targets: it can offer a liquidity window for current investors wishing to withdraw, balance conflicting interests, customise incentives and extend the holding period of the investment targets to maximise their value creation.
Continuation fund transactions are, however, complex transactions, and if the process to arrange them is weak, it often damages the fund manager’s reputation. A successful establishment of a continuation fund requires that the investors are provided with a clear business justification, that the transaction structure is created in a manner that solves the main legal and tax challenges and that the legal and commercial process is efficiently managed.
The Main Contradiction
A substantial portion of continuation fund transactions facilitated by fund managers is never completed. Common reasons for this are disagreements on the fair value and the grounds justifying the transaction. Some investors may be worried about the justifications: is the fund manager actually trying to hold on to a high-quality investment target or is the ultimate purpose of the transaction to dump to the continuation fund unprofitable investment target that could not be realised at an appropriate price on the normal market? There may also be suspicions that the fund manager might want to use a continuation fund to hold on to the fees relating to the investment targets that they would not get if the investment was realised to a third party.
Usually, the dynamics of a continuation fund transaction are more complex than a typical withdrawal from a target company, as in practice the fund manager acts as both parties in the transaction. To create an attractive liquidity alternative, the fund manager must offer the potential buyers an attractive transaction proposal and price.
On the other hand, acting as the seller, the fund manager also has the duty of care towards the existing fund: in practice, the sales cannot be executed unless a sufficient number of existing investors are persuaded to support the sales. Sometimes the fund manager can also ask the buyers for a group commitment to another fund raised by the fund manager, which may increase the complexity of the transaction. When there is a conflict of interests, measures and justifications are necessary to make the transaction credible and satisfactory to both parties.
Starting the Procedure
If you are an investor considering investing in a continuation fund, we recommend consulting advisors at an early stage. The legal documentation of the existing fund and its investment targets should be carefully reviewed so that any required approvals and potential restrictions, such as regulatory issues or transfer restrictions, can be identified.
Tax advice is necessary for the potentially complex structuring of the transactions, in particular, if the existing investors are to invest in the continuation fund in a tax-neutral manner. Financial advisors are often needed to help with the coordination of marketing, the commercial process and investor relations, as well as with proving the transparency and impartiality of the valuation and sales process to the investors. Sometimes further assessments on whether the transactions are market-based are obtained.
As continuation fund transactions are, as a rule, insider transactions, they typically require an approval by the existing fund’s advisory committee or investors. The recommendation is that the fund manager hears the advisory committee before planning the transaction very far. This helps in demonstrating transparency and increasing the investors’ trust, both of which are very important in ensuring a smooth process.
Discovering Buyers and Negotiating Terms and Conditions
After forming the team of advisors, the fund manager should identify potential buyers. These could include single investors or a consortium. Buyers will become investors of the continuation fund and thus provide liquidity for the investors of the earlier fund.
The fund manager can find buyers through their contacts or, for example, through a bidding process. The bidding process is usually managed by the financial advisor who assists in determining the fair value and relieves investors’ concerns relating to the impacts that the fund manager’s conflicts of interests may have on the transaction.
After the potential buyers have been identified, the negotiations that follow can be a significant phase that requires expertise both in funds and in corporate transactions. Even though the terms and conditions of the existing fund can be used as a basis for certain conditions, the central terms and conditions of continuation fund transactions are usually customised. These include financial terms, the fund manager’s own investment, conditions on new investor protection, issues concerning uncalled commitments between current and new investors as well as conditions concerning transferable assets and the minimum number of transferring investors. All existing investors’ side letters should be reviewed, and fund managers should be prepared in case the investors want to renegotiate their side letters at this stage.
As establishing a continuation fund is ordinary fundraising, fund managers should take into account all provisions that are usually applied, such as applications and approvals relating to the marketing of the funds.
What Should Current Investors Take into Account?
A disclosure memorandum is usually drawn up for the current investors. In addition to the details concerning the transaction, the memorandum includes important legal information and often also a form with which the investors can partially withdraw from the current fund or transfer a part of their holdings to the continuation fund.
Often current investors can also make an additional commitment to the continuation fund increasing their relative indirect exposure to the transferring investment targets. Any necessary approvals of the advisory committee and existing investors are also obtained at this stage.
As an exit arranged through a continuation fund deviates from an ordinary exit, it is quite common for the fund agreement to require obtaining an approval of the existing investors. This is usually sensible also considering the fund manager’s liability risks. However, some fund agreements determine permissible inside transfers broadly in such a way that the earlier fund can transfer its holdings in an investment target to any fund managed by the fund manager or its subsidiaries, including a continuation fund.
From the investors’ and fund managers’ point of view, it is recommended that the possibility of establishing a continuation fund is discussed already in conjunction with the fundraising for the original fund in order to avoid surprises towards the end of the fund’s term.
Successful Completion of the Transaction
When investors have decided whether they want to withdraw or transfer their holdings and all preconditions have been fulfilled (e.g. authority approvals have been received), the transaction can be completed. Withdrawing investors are distributed profit, the existing fund can realise the investment target and the continuation fund takes responsibility for holding and developing the investment target.
The key to a successful continuation fund transaction is commencing close cooperation with the investors already at an early stage, and a transparent process for determining the price supports such cooperation. Another critical issue is coordinating the interests of the current and new investors in an appropriate and fair manner, which requires thorough consideration of legal, financial and tax matters.
Latest insights
Article published 13.5.2026 – Venture Capital & Minority Investments
Newly launched Series Seed 4.0 is a comprehensive standard seed financing documentation for the Finnish market

 Article published 28.4.2026 – Private M&A
Unlocking value in carve-outs – Why integration planning deserves top priority in every carve-out
 Article published 14.1.2026 – Tax & Structuring
VAT deductions for private equity investors under the microscope
 Article published 7.11.2025 – Capital Markets & Public M&A
AIFMD II – implications for alternative investment fund managers in Finland

Jarno Tanhuanpää, Tuomas Honkinen & Jussi Mäkikangas
Benjamin Bade, Maiju Mäkinen & Samuli Salminen
Mikko Alakare & Lotta Manu
Hannu Huotilainen & Freja Harima
Latest references
Jolt Capital and Tesi – Investment in VEV
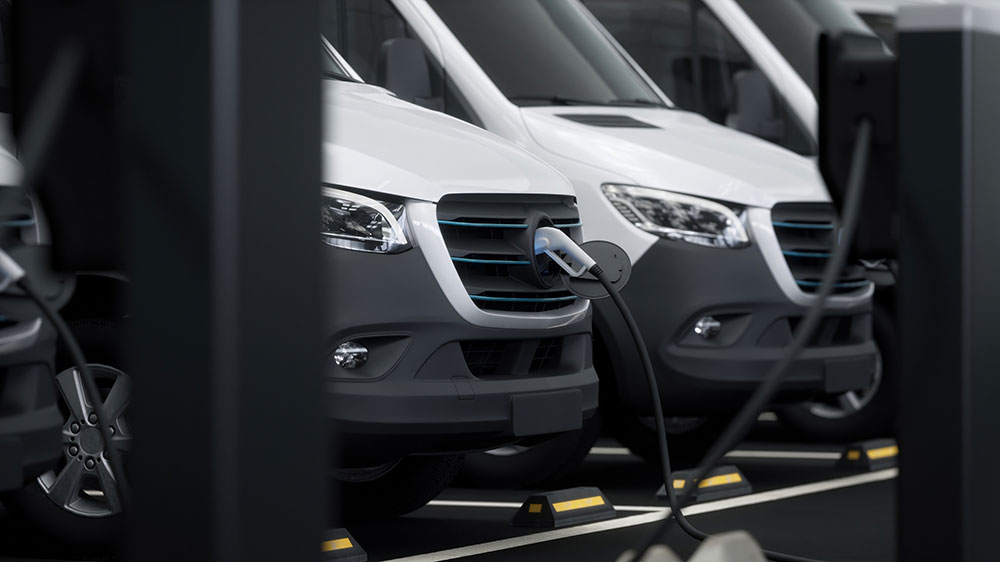
We advised Jolt Capital and Tesi in connection with their investment in VEV, a leading provider of commercial fleet electrification solutions. The investment, led by Jolt Capital with Tesi as co-investor, will support VEV’s next phase of growth and expansion across Europe. As part of the transaction, VEV became an independent company following the acquisition of Vitol’s stake in the business. Founded by Vitol, VEV provides integrated fleet electrification solutions combining fleet strategy, charging infrastructure, energy supply and operational services. Through its VEV IQ platform, the company supports more than 6,000 commercial electric vehicles across Europe and has been deployed across more than 600 sites spanning the transport, logistics and waste sectors. Jolt Capital is a private equity firm focused on growth investments in European deeptech companies. Tesi is a Finnish state-owned investment company that promotes Finnish business and economic growth through investments. We advised Jolt Capital and Tesi on the equity financing and structuring aspects of the transaction. International law firm Goodwin advised the investors on the acquisition of VEV.
Case published 10.9.2026
Topfoods – Acquisition of Delice Plus
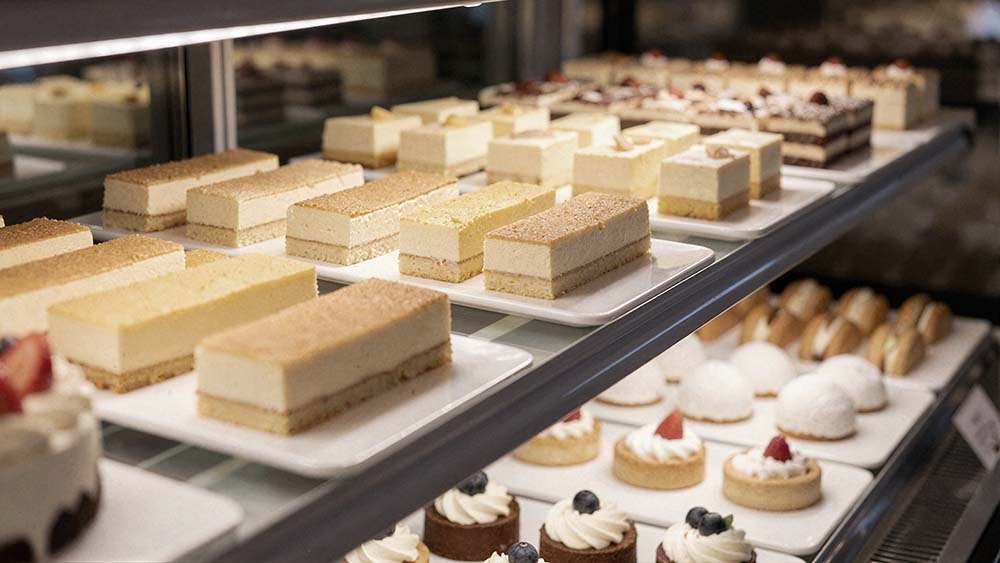
We advised Topfoods Oy, a Triton-backed Geia Group company, on its acquisition of Oy Delice Plus Ab, a Finnish supplier of cakes and pastries. Through the acquisition, Topfoods strengthens its retail business and further reinforces its position in the cakes and pastries segment. Founded in 2008, Topfoods supplies selected food products to professional kitchens, the retail sector, and the food industry.
Case published 4.9.2026
Korona Invest – Sale of Innoflame
We advise Korona Invest and the other shareholders of Innoflame Oy on the sale of Innoflame to Sponsor Capital. The transaction makes Sponsor Capital the new majority owner of Innoflame. Korona Invest has been a shareholder of Innoflame since 2021 and, together with the other selling shareholders, has over the past five years supported the company’s growth, development and several strategically significant corporate transactions, through which Innoflame has strengthened its position as Finland’s leading product media company. The ownership change is intended to support Innoflame’s next phase of growth, including its ambition to build a significant European product media company with the capability to expand rapidly into new markets. The transaction is conditional to the customary closing conditions such as authority approvals. Innoflame is one of Finland’s leading product media specialists, helping its clients build a unified brand experience by offering the design, sourcing and management of product media as a single integrated service. Korona Invest is a Finnish private equity firm founded in 2006, specialising in buyout and growth investments in domestic small and medium-sized enterprises. It makes both majority and minority investments, structuring each project to suit the company’s growth strategy.
Case published 27.8.2026

Ugly Duckling Ventures – EUR 6.5 million funding round of Skyfora
We advised lead investor Ugly Duckling Ventures on the EUR 6.5 million funding round of Skyfora. The round also included Eviny Ventures, LUMO Labs and EIC Fund, alongside non-dilutive funding from Business Finland. The investment will support the commercial scale-up of Skyfora’s weather intelligence solutions, the expansion of partnerships with telecom operators, forecasting providers and meteorological institutions, and the continued growth of the team. Skyfora is a Finnish company developing high-resolution weather data solutions using patented technology that extracts atmospheric data from GNSS receivers embedded in existing infrastructure, such as telecom networks. By unlocking previously untapped data sources, Skyfora enables the next generation of AI-driven weather forecasting and supports improved decision-making across weather-sensitive industries. Ugly Duckling Ventures is a Copenhagen-based venture capital firm focused on early-stage Nordic B2B technology companies, with an emphasis on medtech, resilience tech and business services.
Case published 10.6.2026