A new taxation procedure entered into force from the beginning of 2017 that applies to everyone—you, me and any companies we might own. We discussed this reform on a general level in a recent news update we published. One of the most significant changes relates to the possibility to rectify taxation. The new legislation gives the tax authorities a freer hand to rectify already confirmed taxation after the fact. In this blog post, I dig a little deeper into the amendments.
Tax Authority Given Free Discretion
Under the old rules, the taxation of a particular year could be rectified to the detriment of the tax subject no more than approximately six years after the fact. The key issue was that making a rectification after such a long time had passed required clear fraudulence or error: it was a requirement that the tax subject had either failed to file a tax return entirely or had filed an incomplete, misleading or false tax return. Otherwise the rectification would have to be carried out within a much shorter timeframe or the taxation would remain in force as originally imposed. The old rectification rules will continue to be applied to rectification of taxation for 2016 and preceding years.
As of the start of the 2017 tax year, the requirement for tax subject misconduct was removed. This means that taxation can now be rectified even if the taxpayer has, to the best of its knowledge, submitted correct information to the tax authority if the tax authority interprets the situation differently to the taxpayer.
At the same time, the period for rectifying taxation was shortened to three years. However, the tax authority was given the discretion to extend the rectification period by one year if it receives information affecting taxation exceptionally late or the tax subject is considered to have impeded taxation.
However, there is an exception that is particularly significant to corporations. Under this exception, the rectification period for transfer pricing issues and intra-group financing and structural arrangements is still six years. Despite the rectification period remaining six years, rectification no longer requires fraud or error on the part of the tax subject. That same extended rectification period also applies under certain conditions to rectifications based on information obtained through international information exchanges between tax authorities.
However, rectification is not possible under the new rules if the Tax Administration has already—for example, when carrying out taxation—investigated and expressly decided the matter.
Three Years of Uncertainty?
The new rectification procedure raises many questions. When will the Tax Administration be deemed to have investigated and expressly decided a matter in a way that precludes rectification? Even under the old rules, it has been a challenge to get the Tax Administration to expressly investigate and decide an open tax question even if asked directly via a tax return. At worst, even after receiving a tax decision, taxpayers have remained uncertain of whether the Tax Administration has expressly decided a tax question or not investigated it at all.
Another question relates to when the possibility to rectify taxation ends—or whether it has ended. As the new system allows rectification to be carried out without error on the tax subject’s part, the tax subject has no real way to be sure the result of taxation is final until the three-year period has run out without hearing from the Tax Administration.
In a worst case scenario, the Tax Administration would send a decision on extending the rectification period in the Christmas mail of the last year, which would prolong the uncertainty. One can only hope that the Tax Administration doesn’t start seeing intra-group situations everywhere and handing out extensions just to hold on to its rectification right for as long as possible.
Certainty through Advance Rulings?
The Tax Administration has gained notoriety, among other things, in the case of ‘tax penitents’ who reported their secret foreign investments. Last November, it refused to publish the criteria under which it decided to pass on some—but not all—of the tax penitent cases on to a police investigation. The Tax Administration’s secrecy raised a number of questions concerning the equity of the procedure, which later lead to a complaint to the Parliamentary Ombudsman.
The stated goal of the reform of the rectification process is, among other things, to improve due process for tax subjects. However, if the tax authorities behave as unpredictably and secretively as in the tax penitent case, the results will be a wild contradiction of this goal.
Hopefully these dark clouds remain just bad dreams. This is possible, given that various advance proceedings and more efficient cooperation with its customers have had a prominent place on the Tax Administrations agenda of late.
Only time will tell whether this procedural reform will lead to any big surprises when the time comes to rectify taxation for 2017 and later years. What won’t be the least bit surprising is that advance rulings will grow in importance as corporations seek predictability in their taxation.
Latest insights
Article published 6.2.2026 – Tax & Structuring
Electricity sector Profit Tax Act in conflict with EU law – SAC denied leave to appeal
 Article published 14.1.2026 – Tax & Structuring
VAT deductions for private equity investors under the microscope
 Article published 16.12.2025 – Environment, Energy & Green Transition
Parliament approves substantial increases in tax on mined minerals
 Article published 25.6.2025 – Tax & Structuring
Administrative Court ruling: the Profit Tax Act targeting electricity companies is in conflict with EU law

Janne Juusela & Mikko Alakare
Mikko Alakare & Lotta Manu
Tarja Pirinen, Mikko Alakare & Noora Ahonen
Janne Juusela, Mikko Alakare, Samuli Tarkiainen, Anette Sainio, Noora Ahonen & Joakim Nivala
Latest references
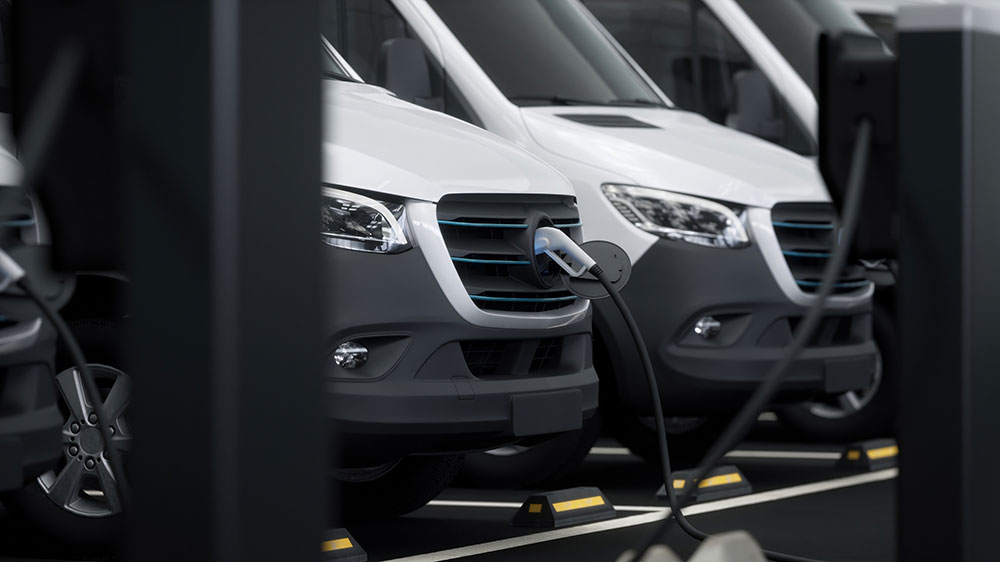
Jolt Capital and Tesi – Investment in VEV
We advised Jolt Capital and Tesi in connection with their investment in VEV, a leading provider of commercial fleet electrification solutions. The investment, led by Jolt Capital with Tesi as co-investor, will support VEV’s next phase of growth and expansion across Europe. As part of the transaction, VEV became an independent company following the acquisition of Vitol’s stake in the business. Founded by Vitol, VEV provides integrated fleet electrification solutions combining fleet strategy, charging infrastructure, energy supply and operational services. Through its VEV IQ platform, the company supports more than 6,000 commercial electric vehicles across Europe and has been deployed across more than 600 sites spanning the transport, logistics and waste sectors. Jolt Capital is a private equity firm focused on growth investments in European deeptech companies. Tesi is a Finnish state-owned investment company that promotes Finnish business and economic growth through investments. We advised Jolt Capital and Tesi on the equity financing and structuring aspects of the transaction. International law firm Goodwin advised the investors on the acquisition of VEV.
Case published 10.9.2026
HANZA – Divestment of its Nivala and Sievi operations
We advised HANZA on the divestment of its Nivala and Sievi operations. The transaction was part of HANZA’s larger strategic reorganisation, where the company optimised its Finnish manufacturing cluster. Founded in 2008, HANZA is a Swedish mechanical engineering and electronics contract manufacturing company listed on the Nasdaq Stockholm main list. HANZA has approximately 5,000 employees and annual sales of SEK 10 billion.
Case published 3.9.2026
Kiwa – Acquisition of Sertio
We advised Kiwa in its acquisition of Sertio Oy, a Finnish notified body designated by the authority in accordance with the EU Regulation on in vitro diagnostic medical devices (IVDR). Sertio provides conformity assessment services in accordance with IVDR. Kiwa is one of the world’s leading testing, inspection, and certification companies, operating in over 35 countries.
Case published 7.5.2026

Metsäkonepalvelu – Acquisition of Junnonen Forest and the business operations of Lamerit
We advised Metsäkonepalvelu Oy in its acquisition of the entire share capital of Junnonen Forest Oy, a Finnish timber harvesting services company, and the timber harvesting services business of Lamerit Oy. The acquisition supports Metsäkonepalvelu’s growth strategy and strengthens the company’s position, particularly in southeastern Finland. Metsäkonepalvelu is a portfolio company of A. Ahlström Oy, a Finnish family-owned industrial owner. The company provides mechanical timber harvesting services to forest companies, large private forest owners, and the public sector in Finland and Sweden. Metsäkonepalvelu Group employs nearly two hundred forestry professionals.
Case published 6.5.2026