This review takes a brief look at recent case law and news. We would be happy to discuss the items in this review with you and the potential effects they may have on your business in more detail.
This review covers

News
Development of Tax Responsibility
On 4 March 2021, the Ministry of Foreign Affairs of Finland published a policy paper to ensure the tax responsibility of companies receiving Finnish development cooperation funding.
The policy paper outlines the key principles that companies receiving development cooperation funding must comply with. The policy is part of Finland’s Taxation for Development Action Programme and applies to all Finnish development cooperation funding to the private sector.
The policy prohibits aggressive tax planning. Aggressive tax planning refers to arrangements by which companies seek to either reduce the amount of taxes they pay or avoid taxes entirely. The policy also prohibits the use of tax havens for investments made using development cooperation funding that are made through investment funds or companies located in a country other than the target country. Companies receiving development cooperation funding are not permitted to distort fair competition by requiring or encouraging tax holidays and other similar tax incentives.
In order to monitor and ensure tax responsible behaviour, companies are also required to transparently report their economic activity as required by the tax authorities in each tax jurisdiction in which they operate.
EU Council Approves Tighter Tax Data Transparency Requirements for Large Multinationals
The ambassadors of the EU member states have mandated the Portuguese presidency to engage in negotiations with the European Parliament for the swift adoption of the proposed public country-by-country reporting (CBCR) directive.
The proposed directive requires multinational enterprises or standalone undertakings with a total consolidated revenue of more than EUR 750 million in each of the last two consecutive financial years to disclose publicly the income tax they pay in each member state, together with other relevant tax-related information.
The reporting obligation would apply to undertakings regardless of whether they are headquartered in the EU or not. The proposed directive is part of the Commission’s action plan on a fairer corporate tax system.
Finnish Government Proposes Removal of Tax Exemption for Small Online Purchases
According to the Government proposal, VAT would in future also be payable when the value of the goods is less than EUR 22 and the shipment arrives from outside the EU. This amendment would implement EU legislation. The amendment is intended to improve the competitive position of EU companies on the market by removing the VAT exemption of shipments from outside the EU.
Approximately 16.5 million shipments of goods valued at under EUR 22 currently arrive in Finland each year. Ending the tax-exemption of imports would increase tax income in Finland by an estimated EUR 26 million.
Companies Must Report COVID-19 Aid in Tax Returns
Financial aid received for business operations due to the COVID-19 pandemic are taxable income for companies and must be recorded in the companies’ books. Companies must also report aid in their tax returns.
Case Law
Personnel Offerings Can Issue Treasury Shares without Losing Tax Benefits
In decision KHO 2021:25 the Supreme Administrative Court assessed whether the benefit received by an employee in a personnel offering based on the employment relationship is taxable only to the extent that the discount on the price of the share is more than ten per cent of the fair price of the share. The shares that were subscribed for in the case were treasury shares held by the company.
The Supreme Administrative Court found that the right to subscribe for shares in the undertaking based on an employment relationship must be interpreted in the same way as share issues under the Limited Liability Companies Act, and thus, treasury shares could be also issued in personnel offerings.
Supreme Administrative Court Preliminary Ruling: Associations Can Be Changed to Cooperatives without Tax Consequences
In case 11.3.2021/107, the Supreme Administrative Court found that an association is not dissolved in taxation when changing its form to a cooperative in such a way that the assets and liabilities relating to its prior activities transfer to the cooperative carrying on the activities.
In the case in question, an association changed into a cooperative in accordance with the Act on Changing an Association Engaged in Commercial Activities into a Cooperative, and a preliminary ruling on the application of section 24 of the Income Tax Act was given in the case.
Administrative Court Decision on Continuation of Business Operations and Applicability of the Tax Relief for Changes of Generation
In unpublished decision 16.12.2021 20/0661/4 of the Vaasa Administrative Court, a legator had gifted shares in a company to their six children as a joint gift. The intention was that all six recipients of the gift would be elected to the board of the company, but that only two recipients at a time would act in the company for two years at a time as part of a board rotation. Two of the recipients worked in management positions in group companies at the time the gift was given and thereafter.
The Administrative Court found that the change of generation provision in the Inheritance and Gift Tax Act was an exception to general tax liability and could not be interpreted expansively. The tax relief for changes of generation requires personal participation in the continuation of business activities. In the proposed board rotation, some of the recipients of the gift would not carry on business operations as board members for several years following the gift of the shares.
The Administrative Court deemed that merely participating in the work of the company’s board for a predetermined time in the future did not constitute a continuation of business activities. Business activities should also continue without separate obstacle immediately after receipt of the gift. The requirement to continue business activities was met with respect to the recipients who worked in group companies. (Not final).
Company Allowed to Deduct VAT Included in Price of Expert Services Purchased for the Acquisition of Shares in Subsidiary
In decision KVL:2020/46, the Central Tax Board found that expert services purchased in connection with the acquisition of the shares of a subsidiary were overhead costs of the company, as the costs were directly linked to the company’s business activities.
The company in the case intended to sell services to the subsidiary to be acquired on a continual basis and to pay VAT on the sale of services. The Central Tax Board deemed that it did not matter whether the expert service purchase agreements were entered into by the company itself or on behalf of the company. It also did not matter whether the company produced the services performed for its subsidiary using its own personnel or whether it procured these administrative services from a third-party subcontractor. (Final).
Losses from Trading in Derivatives on US Markets Were Deductible
In decision KVL:2021/1, the Central Tax Board found that the losses were incurred from investment activities that the applicant was able to engage in in marketplaces either inside or outside the EU.
The characteristics of the marketplaces in question located in the USA were comparable to the concept of regulated markets referred to in the Act on Trading in Financial Instruments. The losses had to be considered comparable to capital losses in the applicant’s taxation, because losses from trading in derivatives on a domestic market and other corresponding marketplaces in the EEA are deductible (Final).
Latest news
Latest references
Efima – Sale of AI business
We advised Efima Oyj on the sale of its AI business to Better Care Technologies Oy. The transaction included Efima’s Moiva AI platform developed for the care sector, the related technology and brand, customer contracts, and the experts working in the business. Efima is a Finnish digital company that supports the sustainable growth of large and mid-sized companies by streamlining their business processes and by creating competitive advantage through the innovative use of artificial intelligence and data. The company has nearly 200 experts based in Helsinki and Tampere.
Case published 21.9.2026
Neoen – Sale of data centre
We advised Neoen Renewables Finland Oy, part of the French Neoen Group, in its sale of a data centre project to a consortium consisting of international data centre developers and operators. This marked Neoen’s first data centre development project in Finland. Founded in 2008, Neoen is one of the world’s leading independent renewable energy producers. The company operates in 15 countries. It develops, finances, builds, owns, and operates solar power plants, wind farms, and battery storage systems. Neoen Group is owned by global alternative asset manager Brookfield Corporation.
Case published 17.9.2026
Jolt Capital and Tesi – Investment in VEV
We advised Jolt Capital and Tesi in connection with their investment in VEV, a leading provider of commercial fleet electrification solutions. The investment, led by Jolt Capital with Tesi as co-investor, will support VEV’s next phase of growth and expansion across Europe. As part of the transaction, VEV became an independent company following the acquisition of Vitol’s stake in the business. Founded by Vitol, VEV provides integrated fleet electrification solutions combining fleet strategy, charging infrastructure, energy supply and operational services. Through its VEV IQ platform, the company supports more than 6,000 commercial electric vehicles across Europe and has been deployed across more than 600 sites spanning the transport, logistics and waste sectors. Jolt Capital is a private equity firm focused on growth investments in European deeptech companies. Tesi is a Finnish state-owned investment company that promotes Finnish business and economic growth through investments. We advised Jolt Capital and Tesi on the equity financing and structuring aspects of the transaction. International law firm Goodwin advised the investors on the acquisition of VEV.
Case published 10.9.2026
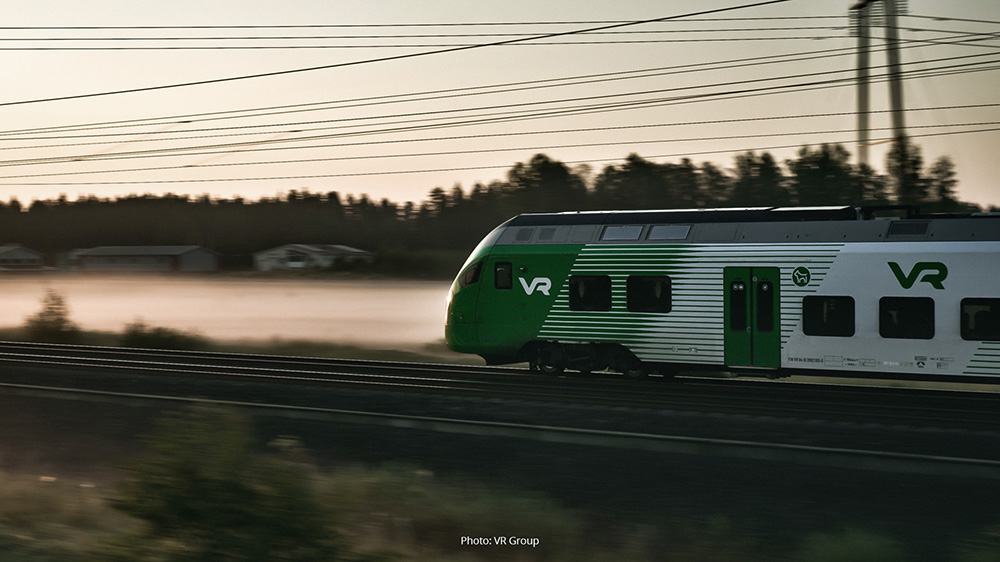
VR Group – Intellectual property matters
VR-Group Plc is a transport and logistics group owned by the Finnish State, operating passenger and freight rail transport in Finland with activities also in the Swedish market. VR Group provides passenger, logistics and maintenance services with over 160 years’ experience in developing responsible transport of the future. We advise VR Group in intellectual property matters as part of the company’s wider brand protection efforts. Our assignments have included advice on copyright, design rights and trademarks, focusing on the protection of the company’s visual identity – including its distinctive green colour – in connection with transport services as part of a comprehensive IP protection strategy. VR Group’s consistent brand building has also received recognition, including the Finland Chamber of Commerce’s Brand of the Year award in 2026. In the competition, brands were viewed comprehensively from various perspectives, including their story, strategic role, brand renewal ability and intellectual property protection. The jury found that VR had understood the importance of the protection of its brand as part of a comprehensive business strategy.
Case published 9.9.2026