In this legal bulletin we would like to draw your attention to the amendments that have been made to the Tax Code that entered into force in January 2017 regarding value added taxation of digital services rendered by foreign companies in Russia. These amendments have been introduced by the Federal Law No. 244-ФЗ dated 03.07.2016 “On the amendments to Parts One and Two of the Tax Code of the Russian Federation”.
21.3.2017
Changes to Taxation of Digital Services in Russia
What Has Changed
From now on, foreign companies providing services to Russian consumers by digital means via the Internet must: (i) apply for registration with the Russian Tax Authorities and (ii) charge and pay Russian value added tax (VAT).
Whom It Concerns
Foreign companies in the e-commerce industry operating on the Russian market (e.g. Google, Microsoft, Apple, Netflix, etc.). The aforementioned companies have registered within the Russian Tax Authorities in January-February 2017.
Internet services that are considered taxable activities:
Internet services that are not considered taxable activities (exhaustive list):
Tax is payable in any of the following circumstances:
Registration with the Tax Authorities
Foreign companies shall register with the Russian Tax Authorities within 30 days of starting their business activities. The deadline for registration for companies already doing business in Russia at the time of the new law’s enactment was 31 January 2017. Companies that have not registered by this deadline are advised to do so without delay.
If the company is doing business through a foreign company acting as agent, such agent will also need to register with the Tax Authorities. If a foreign company is doing business through a Russian agent, the Russian company is already registered with the Tax Authorities and will serve as the tax agent for the foreign company (i.e. will withhold and pay VAT for the foreign company).
PLEASE NOTE: registration with the Tax Authorities and payment of Russian VAT does not constitute a permanent establishment for the foreign company.
Document flow between the foreign companies and the Tax Authorities is handled through the company’s personal online account. Login credentials for the account are provided by the Tax Authority at the time of registration.
Tax Rate and Payment
The tax rate is 15.25%. Russian accounting rules for VAT are not applicable (i.e. no VAT invoices or purchase/sales ledgers are required).
The first tax period for the foreign companies is January to March 2017. The companies must provide VAT records and pay the tax no later than 25 April 2017.
Foreign companies cannot apply for VAT deductions in this case, however, they can apply to for tax credit/refund of excessively paid tax.
The Tax Authorities may conduct in-office inspections with regard to the calculation and payment of VAT, request information from a foreign company as well as use other means to levy the tax.
Latest news
Latest references
Cibus Real Estate – Acquisition of three retail properties
We advised Cibus Real Estate AB (publ) on its acquisition of three newly built retail properties in Pori, Finland. Kesko is the tenant in all three properties, and the average lease term is 8.1 years. Cibus is a real estate company listed on Nasdaq Stockholm Mid Cap. The company’s business concept is to acquire, develop and manage properties in Europe with daily goods chains as anchor tenants. The company currently owns approximately 700 properties in Europe.
Case published 12.11.2026
Seaya Nova and Molten Ventures – USD 80 million series C financing of Pliant
We advised Seaya Nova and Molten Ventures as Finnish counsel in connection with the USD 80 million Series C financing of Pliant, a Berlin-based fintech specialising in B2B payment solutions and corporate credit cards. The financing round was led by Seaya Nova and Speedinvest, with participation from Illuminate Financial, Motive Partners, Molten Ventures and Citi Ventures. Founded in Berlin in 2020, Pliant provides modular payment solutions for businesses and holds an EU e-money licence in Finland as well as a licence from the UK Financial Conduct Authority. We advised on the Finnish law aspects of the transaction alongside YPOG, which acted as lead counsel to Seaya Nova and Molten Ventures.
Case published 12.11.2026
Nala Renewables – Development, acquisition and financing of battery energy storage system (BESS) project
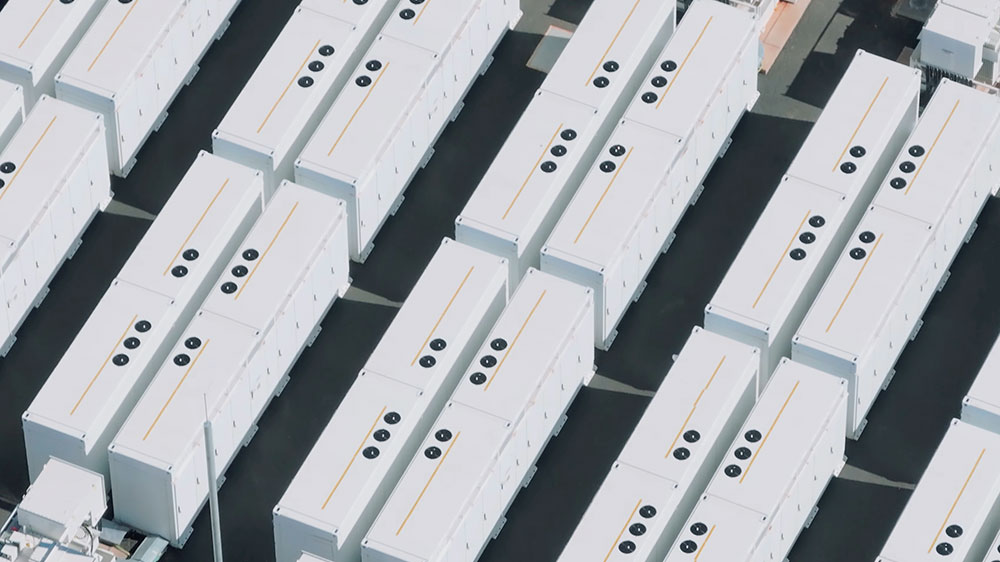
We advised Nala Renewables on the Finnish law aspects of the development, acquisition and financing of its battery energy storage system (BESS) project in Vuolijoki, Finland. The project comprises a 125 MW / 250 MWh battery energy storage system. Our advice extended beyond financing to the transaction’s legal due diligence and the acquisition of the project company. We also advised on key project contracts and financing documentation for the project finance facilities provided by Coöperatieve Rabobank U.A. The project is part of Nala Renewables’ growing portfolio of battery storage assets in Finland and the wider Nordic region, supporting the integration of renewable energy and contributing to the flexibility and stability of the Finnish electricity grid.
Case published 3.11.2026
Foundation Clinic – Funding Round
We advised Foundation Clinic in connection with its funding round backed by a group of prominent Finnish technology entrepreneurs and investors, including founders behind Supercell and Wolt. Foundation Clinic is a Finnish healthcare company developing a new approach to private healthcare focused on preventive, data-driven and continuous care. The company aims to combine comprehensive health data with ongoing medical care to identify and address health risks at an early stage.
Case published 29.10.2026